

What you'll learn: concise, actionable steps to accept credit cards safely and profitably, why Mr.Truby has been in payment processing for over 20 years, and how to reach him at 928-706-6769 or just go this page. This article prioritizes merchant outcomes—speed of setup, costs, security (PCI), and terminal vs. gateway choices—so you can decide the next step quickly.
Key Takeaways
- Phone or page contact: Mr.Truby, 928-706-6769, simplifies onboarding for small businesses.
- Choose between countertop terminals, mobile POS, or gateway integrations based on sales channel and risk.
- Prioritize PCI-compliant options and tokenization to reduce fraud liability.
How can Mr.Truby get my business processing cards fast?
Expect a practical intake: business type, average ticket, monthly volume, and risk profile determine the route—merchant account with an acquiring bank, an ISO aggregator, or a payment facilitator model. Mr.Truby's 20+ years focus means he can match a merchant to a suitable provider and terminal within days for standard retail and within 1–2 weeks for integrated e-commerce setups.
What the onboarding process looks like
Documentation typically includes your EIN/SSN, voided check, processing history, and ID verification. For higher-risk verticals, underwriters request more detail; expect conditional holds or rolling reserves. Having organized financials shortens approval timelines.
Which payment stack fits my business: terminal, mobile POS, or gateway?
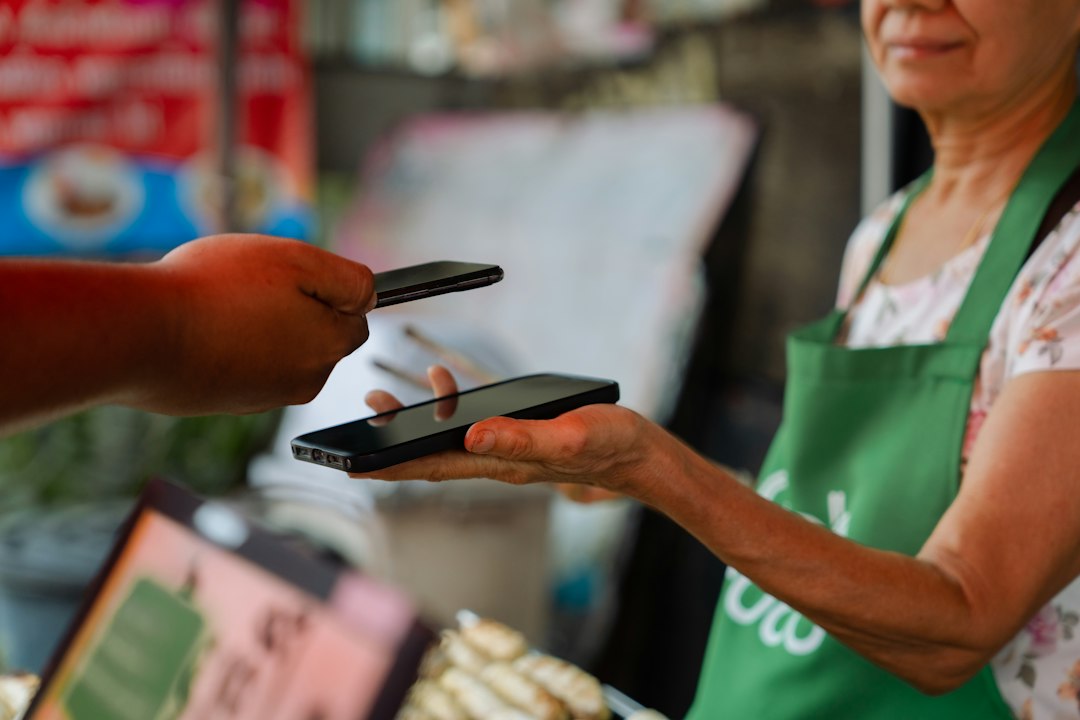
Decision depends on where sales occur. Use a countertop EMV terminal for fixed locations, a mobile POS for on-the-go sales (card present via NFC/contactless), and a payment gateway/API for e-commerce or recurring billing. Mr.Truby evaluates interchange costs and suggests the lowest-fee path when possible.
Interchange and fees — practical perspective
Interchange is set by card networks; processors add markup. For transparency, request an interchange-plus pricing table. If you have many keyed transactions, demand level 2/3 support to reduce interchange costs on business cards.
How do I manage security and compliance without disrupting sales?
Prioritize point-to-point encryption (P2PE) and tokenization to shift data handling away from your systems. These reduce PCI DSS scope and materially lower breach risk. For authoritative guidance on standards and merchant responsibilities, consult the PCI Security Standards Council guidance.
Operational steps to reduce liability
Use certified terminals, keep firmware current, and avoid storing PANs on local systems. For e-commerce, implement hosted checkout or tokenization. Mr.Truby typically recommends vendors offering out-of-scope solutions first to minimize configuration work.
What about chargebacks, disputes, and risk management?
Chargebacks are governed by card network rules and your processor's dispute workflow. Effective defenses: clear refund policies, stored AVS/CVV logs, and timely capture of proof of delivery. Mr.Truby advises active monitoring and a documented returns process to reduce chargeback rate.
When to contest a chargeback
Contesting is worth it when you have conclusive evidence (signed receipts, delivery confirmation, IP and device data for online sales). For small-value disputes, balance contest cost vs potential recovery; frequent contesting without evidence increases operational expense.
Examples and expert-backed context
Example 1: A coffee shop moved from keyed transactions to an EMV countertop terminal plus contactless tap-to-pay; fraud exposure dropped because card-present transactions carry lower fraud risk. Example 2: A subscription SaaS implemented a gateway with tokenization and saw retries and dunning automation reduce involuntary churn. These approaches reflect best practices endorsed by payment security authorities and experienced processors.
When costs outweigh benefits
If monthly volume is under a modest threshold and average ticket is low, an aggregator or pay-as-you-go processor may be cheaper despite higher per-transaction fees. Mr.Truby evaluates break-even points and recommends the setup that minimizes total cost of acceptance.
Next step: call 928-706-6769 for an immediate, no-pressure assessment tailored to your sales channels and risk profile, or just go this page for more details. Expect a clear recommendation—terminal, gateway, or hybrid—and a timeline to start accepting credit cards within days for most small businesses.