

In this article you will learn how Mr.Truby has been in payment processing for over 20 years now, what that experience means for your merchant account, and concrete steps to start accepting credit cards — call 928-706-6769 or just go this page. The primary keyword appears early so you immediately know the article focuses on Mr.Truby's two decades in payments and practical help for business owners.
Key Takeaways
- Mr.Truby provides merchant services rooted in 20+ years of payment processing experience.
- Practical benefits include faster underwriting, fee transparency, and tailored PCI-aware setups.
- Call 928-706-6769 or just go this page to get a direct evaluation for card acceptance.
How can Mr. Truby help my business accept credit cards right now?
He evaluates your current sales channels and recommends an actionable solution: countertop POS, mobile reader, or integrated payment gateway for e-commerce. With over 20 years in payment processing, Mr.Truby can quickly identify the lowest-friction path to accept cards based on your transaction mix and customer behavior.
Expect a short onboarding checklist: merchant underwriting, hardware selection, gateway configuration, and PCI compliance guidance. This is a practical, outcome-focused engagement rather than a generic sales pitch.
What tangible advantages come from two decades of payment industry experience?
Longevity in payments correlates with institutional knowledge of interchange categories, underwriting criteria, and risk profiling. Mr.Truby's experience reduces trial-and-error: he knows which account types underwriters prefer for specific verticals and which pricing models hide fees.
Experience also shows in dispute management. Seasoned processors design workflows to reduce chargeback rates and accelerate representment when legitimate sales are disputed. That operational maturity impacts your bottom line faster than marginal rate reductions.
Technical and compliance strengths
Expect guidance on EMV terminals, tokenization, and contactless (NFC) acceptance to reduce fraud exposure. For compliance, Mr.Truby advises on meeting industry standards such as those from the PCI Security Standards Council, which define data-protection requirements for card acceptance systems. See the official PCI Security Standards Council guidance for technical controls and validation options.
How does onboarding and integration work for different business types?
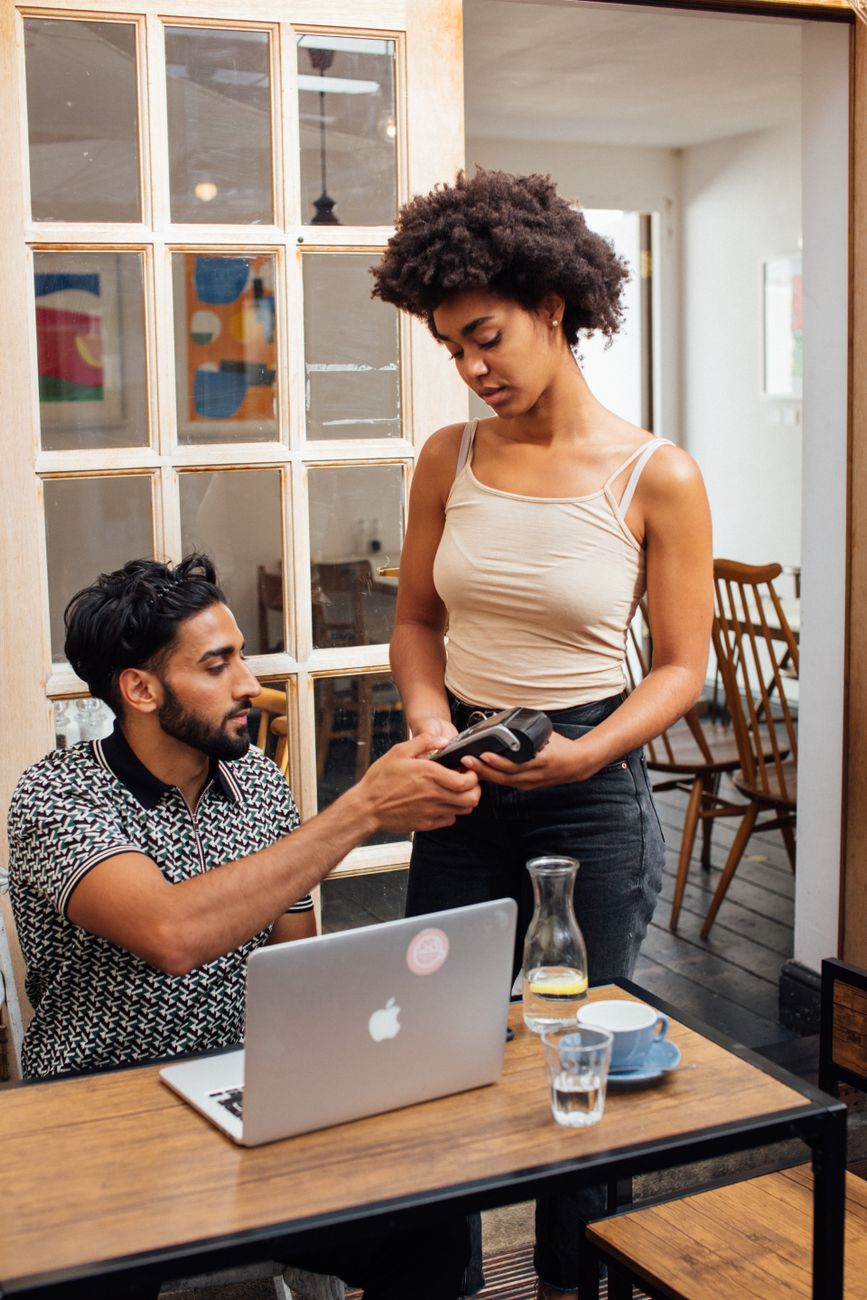
Small retail: a countertop POS with EMV and NFC, paired with simple monthly reporting and reconciliation tools. Mobile vendors: a PCI-validated mobile card reader and a merchant account enabling keyed or tapped transactions. E-commerce: payment gateway integration, hosted checkout options, and tokenization to limit storage of card data.
Integration timelines vary but should be goal-oriented: payment acceptance within days for basic setups and two to four weeks for customized API integrations. Mr.Truby's role is to map dependencies—gateway credentials, developer access, and PCI self-assessment—so you avoid common delays.
What common pitfalls do businesses face, and how does Mr. Truby mitigate them?
Hidden fees and complex pricing schedules are frequent pain points. Mr.Truby performs line-by-line reviews of merchant agreements to highlight per-transaction fees, monthly minimums, and early-termination conditions. Transparency is emphasized: know the interchange, processor markup, and monthly service charges up front.
Another pitfall is underestimating fraud controls. He recommends a layered approach—EMV, AVS/CVV checks, velocity rules, and tokenization—aligned to your transaction profile so controls don't harm legitimate sales volume.
Examples and expert-backed context
Example 1 — Local café: Switched to a countertop EMV terminal and a flat monthly fee, reducing reconciliation time and eliminating surcharge surprises at month-end.
Example 2 — Subscription service: Implemented tokenization and recurring-billing gateway features to reduce failed payments and lower churn.
Expert context: industry standards like PCI DSS focus on protecting cardholder data throughout processing and storage; aligning your setup with these standards reduces breach risk and regulatory exposure. The PCI Security Standards Council provides the authoritative baseline for these practices.
What decision framework should a business owner use when evaluating a payments partner?
Ask four outcome-focused questions: Will this partner reduce operational friction? Can they support my sales channels? Are fees transparent and justified? Do they provide clear compliance guidance? Mr.Truby structures proposals around these questions so you can compare offers on outcomes rather than sales language.
Seek a short pilot or proof-of-concept when possible. A two-week or one-month trial with defined metrics (authorization success, settlement speed, chargeback rate) will quickly show whether a provider meets your operational needs.
Next step: for a direct evaluation tailored to your business, call 928-706-6769 or just go this page and request a no-obligation merchant review. That will produce a clear, actionable plan to accept credit cards with minimal disruption.