
Many small business owners feel squeezed by the steady drain of processing fees—charges for payments, card transactions, and certain software services. The good news is that affordable and targeted technology upgrades can significantly reduce those costs and improve overall profitability. This guide explains what these upgrades are, why they matter, and how to begin adopting them step by step. No technical background required; you'll get simple explanations, real-world examples, and small actions you can take right away.
Introduction: What this guide covers and what you'll learn
This guide will help you identify practical, low-cost technology improvements that reduce transaction and operational fees. You'll learn: what common fees exist, the most effective tech upgrades to cut them, basic concepts behind each upgrade, how to start applying changes without disrupting your business, and mistakes to avoid. Think of this as a map: you won't need to be an IT expert to follow it—just willing to take a few manageable steps.
What are these tech upgrades?
When we talk about tech upgrades here, we mean both hardware and software changes that lower the amount you spend to process payments and run daily operations. Examples include modern point-of-sale hardware, smarter payment routing, cloud-based services, automated invoicing, and improved network security. In short, these upgrades help you accept money more cheaply, automate repetitive tasks so staff time costs less, and reduce errors that lead to hidden fees.
Why does it matter?
Cutting processing costs increases your net profit without raising prices or requiring more sales. That extra margin can pay for marketing, hiring, better inventory, or simply provide a safety buffer. Beyond money, better tech reduces stress, saves time, and makes customer interactions smoother—customers notice quick, clear checkout experiences. For small businesses operating on tight margins, even a small percentage reduction in fees can translate into meaningful annual savings.
Core concept: Payment processing optimization
Payment processing optimization means choosing how you accept and route payments to minimize fees. Payment fees vary by card type, method (chip, swipe, contactless, online), and how the transaction is routed. Like choosing the best lane at a grocery store to check out faster and cheaper, smart payment routing directs transactions by the most cost-effective method.
Simple steps
- Compare rates from multiple payment processors instead of accepting the default from your bank.
- Use processors that offer interchange-plus pricing, where you see the actual card cost and a clear markup, rather than bundled opaque plans.
- Batch similar transactions when possible—grouped processing can reduce per-transaction fees.
Core concept: Modern point-of-sale (POS) systems
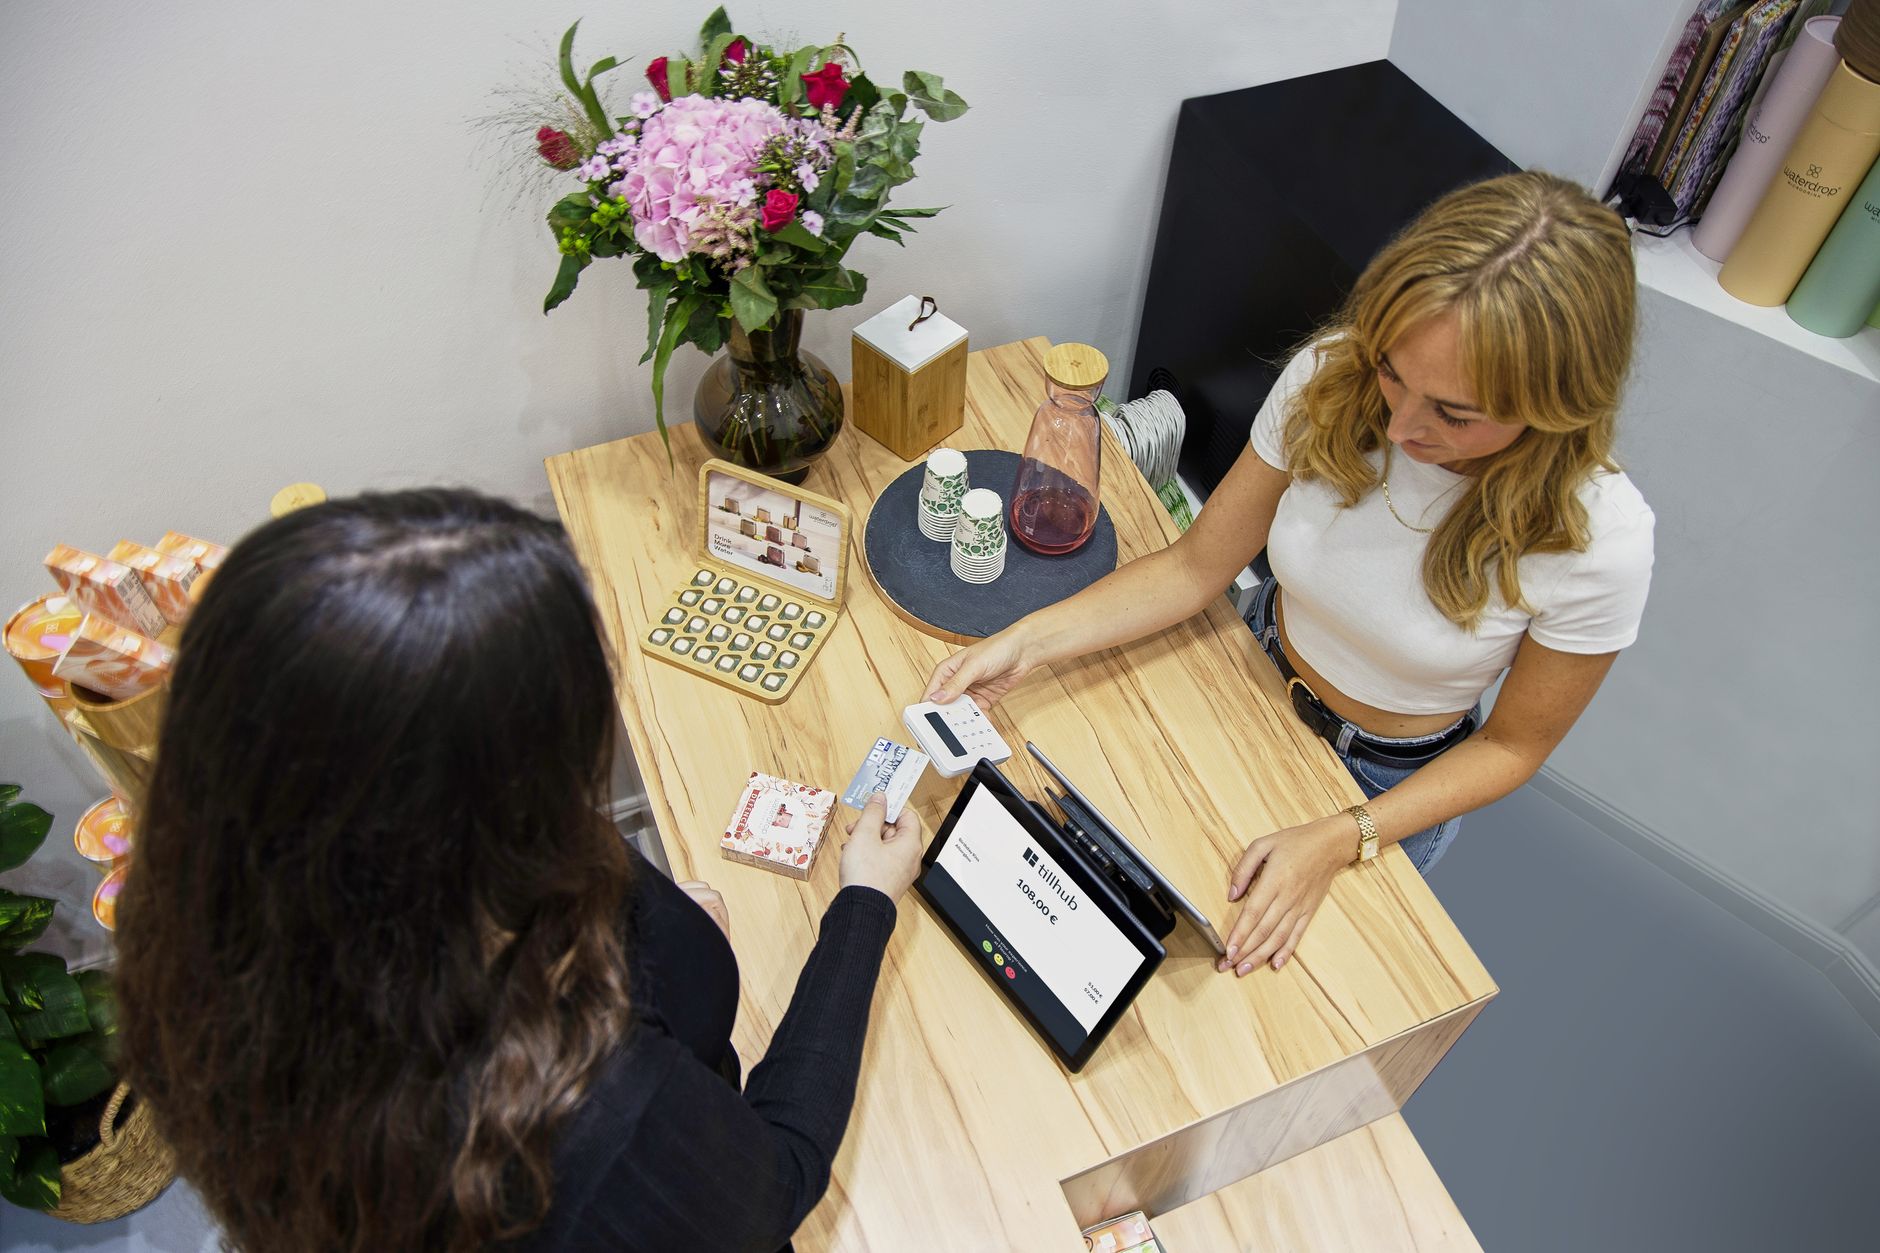
A modern POS combines hardware and software to handle sales, inventory, and customer data. Older registers may charge extra for features or force you into expensive contracts. Replacing them with flexible cloud-connected POS platforms often saves money by consolidating tools and improving efficiency.
Real-world example
A coffee shop replaces a legacy register and separate card reader with a cloud POS that includes inventory tracking and sales reports. The owner saves on a monthly subscription that bundled several services separately and reduces card processing fees by using a more competitive processor integrated into the POS.
Core concept: Cloud services and software consolidation
Cloud services host software on remote servers you access online. Moving to cloud-based accounting, payroll, scheduling, and inventory reduces the need for on-site servers and maintenance. It also allows consolidation—using one platform for multiple functions—often cheaper than multiple single-purpose tools.
Benefits
- Lower upfront hardware costs and fewer maintenance headaches.
- Automatic updates and security patches managed by providers.
- Better integration between systems, reducing manual work and human error.
Core concept: Automation of repetitive workflows
Automation means setting up software to perform routine tasks—like invoicing, receipts, reconciliations, and inventory alerts—without manual effort. It is like programming a reliable helper who never forgets a task. Automation saves staff time, reduces mistakes that cause chargebacks or late fees, and speeds billing so you get paid faster.
Examples of automation
- Automatic invoicing for recurring customers.
- Auto-reconciliation between your sales platform and bank statements.
- Automatic low-stock alerts to avoid rush orders or stockouts.
Core concept: Hardware upgrades that matter
Not all hardware is equal. Upgrading to EMV and contactless-enabled card readers reduces fraud-related chargebacks. Faster, more reliable Wi-Fi reduces failed transactions and manual card-keying—an action that often results in higher fees because it's treated as a higher-risk transaction.
What to choose
- EMV and NFC-capable terminals: support chip and contactless cards and mobile wallets.
- Reliable routers and backup internet options: minimize downtime that leads to offline processing fees.
- Affordable tablets or terminals that run modern POS apps instead of legacy cash registers.
Core concept: Data analytics to reduce fees
Using basic analytics—simple reports and dashboards—helps you spot expensive patterns, like certain products that trigger more refunds or payment methods that cost more. Think of analytics like a magnifying glass that shows small leaks in your boat before they sink it.
What to track
- Fee-per-transaction by payment type.
- Refunds and chargebacks: frequency and reason.
- Sales volume at different times: prioritize cheaper batch processing windows when possible.
Core concept: API integration and smart routing
APIs (Application Programming Interfaces) let different software systems talk to each other. Integrations enable smart routing of payments to the most cost-effective channel or processor automatically. This is like setting up plumbing that sends water where it's cheapest to flow.
Beginner-friendly approach
You don't need to code. Many modern platforms offer pre-built integrations or marketplace plugins that connect your POS, accounting, and payment processor.
Getting started: First steps for beginners
Follow these practical steps to begin cutting costs without disrupting operations:
- Audit current costs: Collect 3 months of statements from payment processors, banks, and major SaaS tools to see where money flows.
- List pain points: Document slow processes, frequent refunds, and hardware downtime that cause extra fees.
- Prioritize low-cost, high-impact upgrades: Replace outdated card readers, switch to a clearer pricing processor, or move one manual task to an automated workflow.
- Test one change at a time: Swap a card reader or enable batch invoicing first so you can measure results and learn.
- Use trials and demos: Most cloud providers offer free trials—use them to test before committing.
Common mistakes to avoid
- Rushing to the cheapest processor without understanding fine print: low headline rates can hide monthly minimums, chargeback fees, or long contracts.
- Replacing everything at once: large simultaneous changes increase risk and make it hard to know what worked.
- Ignoring security: cheaper hardware or software that neglects security can cause costly breaches and fees.
- Not training staff: new tools are only effective if your team knows how to use them. Small training sessions prevent errors that lead to fees.
- Neglecting customer experience: cost savings should not make checkout slower or more confusing for customers.
Resources and next steps for further learning
To deepen your knowledge, use these accessible resources:
- Processor comparison guides from independent blogs—look for articles that explain interchange-plus pricing.
- Vendor webinars and free demos—see how POS systems and payment gateways actually work in practice.
- Local small business centers or chambers of commerce—many offer workshops on tech and finances.
- Beginner courses on cloud software and basic analytics from free platforms like Coursera or YouTube channels targeted at small businesses.
- Forums and communities—join small business groups on social networks to ask peers what worked for them.
Improving your tech to reduce processing costs is a step-by-step journey. Start small, measure results, and scale what works. You don't need to be perfect—just curious and willing to try one manageable improvement.
Take one simple action today: collect your last three months of payment processor and bank statements into a single folder, and highlight the total processing fees for each month. That single number will make it clear how much you can potentially save and is the first step toward picking an upgrade that pays for itself.