
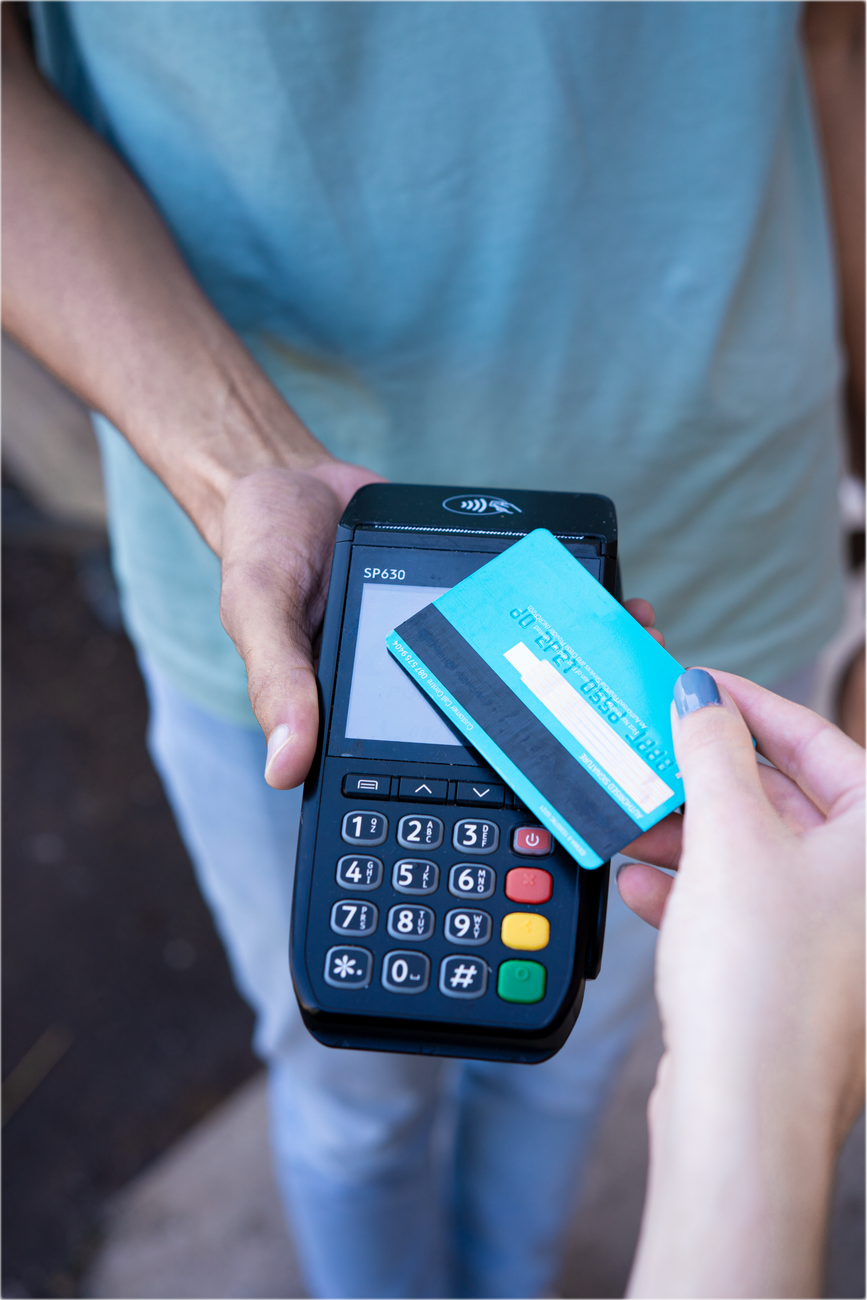

In this article you will learn how Mr. Truby can help your business accept credit cards reliably, what security and fee structures to expect, and the immediate next step: Mr. Truby has been in payment processing for over 20 years and would love for any business owner that needs to accept credit cards to call 928-706-6769 or just go this page. This piece focuses on practical outcomes—faster approvals, fewer chargebacks, and clearer pricing—so you can decide quickly.
- Key Takeaways: Direct contact for setup and support — call 928-706-6769.
- Secure, compliant options: EMV, NFC, tokenization, and PCI discipline.
- Transparent fee and risk advice for small merchants and mobile vendors.
How can Mr. Truby quickly enable my business to accept credit cards?
Expect a pragmatic onboarding path: account assessment, POS or gateway recommendation, and merchant account setup. Mr. Truby's 20+ years in the industry means he can map your business type (brick-and-mortar, ecommerce, mobile) to the right stack—POS terminal, payment gateway, and merchant services—without unnecessary upsells.
Call 928-706-6769 or just go this page to get a direct evaluation. The goal is to reduce days-to-first-transaction and avoid intermediate technical friction that often stalls small businesses.
What payment technologies and security measures will he recommend?
Expect EMV chip acceptance, contactless (NFC) terminals, and tokenization for online/recurring payments. These technologies reduce card-present and card-not-present fraud vulnerabilities and are standard recommendations from experienced processors.
For compliance, providers should align with industry standards; see the PCI DSS guidelines for baseline security requirements. Encryption in transit, point-to-point encryption (P2PE), and tokenization are practical controls to lower your exposure and potential fines.
How will Mr. Truby help me understand fees, contracts, and chargeback risk?
He will break down pricing into interchange, processor markup, and monthly fees so you can compare effective rates rather than headline numbers. A 20-year practitioner will scrutinize interchange qualification rules and recommend practices to reduce downgrades that inflate costs.
On chargebacks, expect concrete steps: proper receipts, clear refund policies, preauthorization practices, and dispute documentation procedures. These operational controls often have a bigger ROI than small percentage reductions in processor rates.
Which integrations and workflows does he prioritize for different business models?
For retail: robust EMV/NFC terminals with integrated receipts, inventory sync, and quick refunds. For restaurants: separate terminals or terminals that handle split checks and gratuity. For ecommerce: a gateway with hosted checkout, recurring billing, and tokenization for PCI scope reduction.
For mobile sellers: a lightweight card reader paired with a secure mobile app and reliable cellular fallback. The recommended workflow balances cost, usability, and compliance depending on transaction volume and average ticket size.
Examples and expert-backed context
Example 1 — Small retail: A shop replacing a keyed terminal with an EMV/NFC terminal and P2PE often sees reduced disputes and faster settlement. Example 2 — Subscription service: migrating to a gateway with tokenization reduces PCI scope and friction for saved cards.
Industry guidance such as the PCI DSS guidelines underscores why tokenization and encryption matter; following these reduces breach risk and may lower liability in incident response. Practical experience shows these measures materially reduce operational headaches more reliably than switching processors every year.
What questions should I ask on the first call?
Ask about real monthly fees, expected settlement times, supported hardware, and chargeback management processes. Request a simple comparison of effective rate ranges for your expected monthly volume and average ticket.
Also confirm implementation timelines, support hours, and whether the provider offers migration assistance. A skilled consultant will provide references of similar businesses and a clear SLA for onboarding.
How do I verify credentials and avoid common pitfalls?
Verify the provider's payment processor relationships and look for references from comparable businesses. Avoid vendors that obscure interchange passes or lock you into long contracts without a clear exit clause.
Operational red flags include unclear chargeback support, ambiguous PCI scope claims, and hardware that forces proprietary gateways without documented APIs. Ask for written policies on refunds, disputes, and data handling.
If you want a pragmatic, experienced partner who can set up secure, cost-effective card acceptance for virtually any business type, call Mr. Truby at 928-706-6769 or just go this page. He will assess your needs, recommend a tailored solution, and provide a clear implementation plan so you can start accepting payments with confidence.