
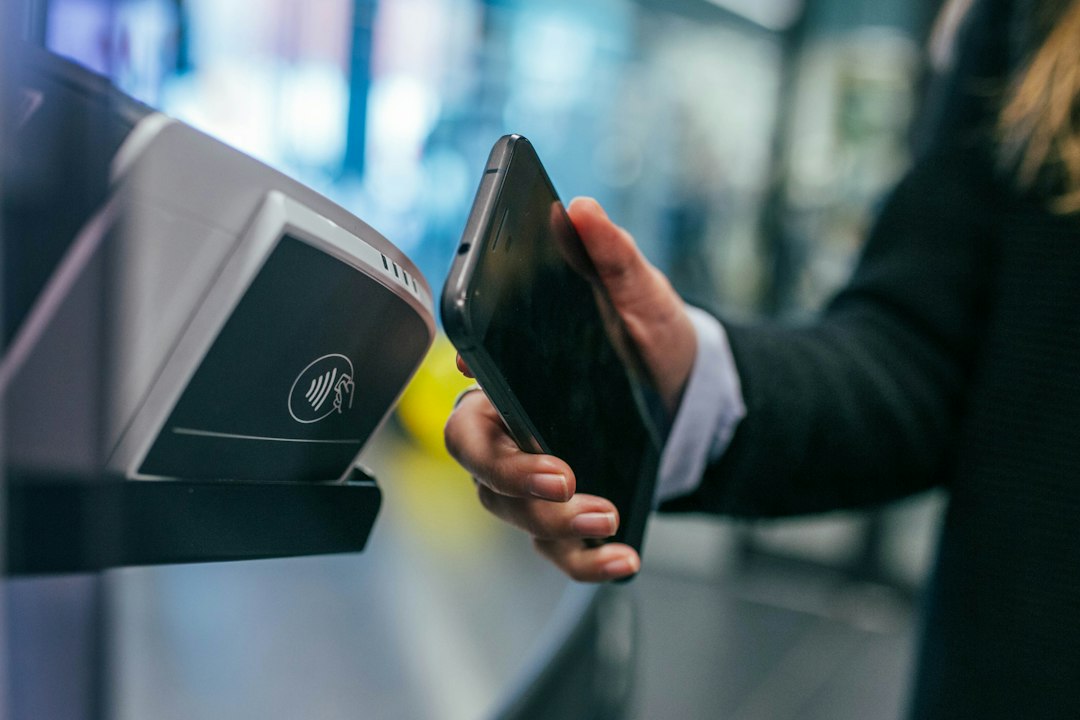

Choosing credit card processing services means finding a secure, practical way to accept payments without letting fees, confusing terms, or slow deposits disrupt your business. This guide explains how credit card processing works, what to compare among credit card processing companies, and how to choose a setup that fits your sales channels and customers. Whether you sell in person, online, or both, the right provider can make checkout smoother and payment operations easier to manage.
Key Takeaways
- Compare total costs, including processing rates, monthly charges, and possible add-on fees.
- Match the payment tools to how you sell: in person, online, by invoice, or across channels.
- Review security, customer support, funding schedules, and contract terms before applying.
How does credit card processing work?
A card payment moves through several connected parties. A payment gateway or point-of-sale (POS) system captures the transaction, the processor sends it to the card network, and the customer's issuing bank approves or declines it. If approved, funds are later settled to the merchant's account, minus applicable fees.
These steps often happen in seconds, but the experience depends on each part working together. A provider may supply a card reader, online checkout tools, a virtual terminal, reporting, and access to payment processing infrastructure—or integrate with tools you already use. Ask which services are included and which require separate vendors or subscriptions.
Which credit card processing services fit your business?
Start with your everyday payment scenarios, not a list of features. A café may need a countertop terminal, contactless payments, and quick staff workflows. A consultant might prioritize payment links, recurring billing, and invoices. An online retailer may need a hosted checkout, ecommerce integrations, and tools for handling refunds and disputed transactions.
Consider whether you need to accept credit and debit cards, mobile wallets, or payments keyed in by phone. If you sell both online and in person, look for a setup that can bring sales and reporting into one view. Also check hardware compatibility, integration with accounting or inventory software, and the process for adding locations or users as your business grows.
How can you compare credit card processing companies?
Compare providers using the same checklist and realistic examples from your business. Request a clear explanation of the pricing model: interchange-plus, flat-rate, or tiered pricing. The total you pay can depend on transaction type, card brand, how the payment is accepted, and any provider charges. A headline rate alone does not reveal the full cost.
Ask for an itemized list of potential fees, such as monthly service charges, terminal costs, chargeback fees, PCI-related fees, and early termination charges. Confirm deposit timing, reserve or hold policies, customer support availability, and how disputes are handled. Read the service agreement carefully, especially terms about automatic renewal and equipment returns.
Check payment security and compliance
Security should be part of your comparison, not an afterthought. Ask how the provider supports secure card acceptance, protects payment data, and helps merchants meet applicable obligations. The PCI Security Standards Council's PCI DSS overview explains the payment-card data security standard and why protecting cardholder information matters.
Do not assume that using a processor automatically removes every security responsibility from your business. Responsibilities can vary with your payment setup and the services you use. Ask the provider what steps are required for your specific environment, and use supported hardware and software with current security updates.
What should you verify before choosing a provider?
Look beyond the sales pitch. Confirm that the company supports your business type, sales volume, and expected transaction patterns. Ask how quickly you can reach a knowledgeable support representative when a terminal fails or a payment is delayed. Find out whether the provider offers onboarding assistance and clear instructions for refunds, chargebacks, and account changes.
It is also sensible to review the application requirements before starting. Providers may request business and ownership details, bank information, and documents used to verify identity or operations. Accurate, consistent information can help the review proceed smoothly, though approval and timing depend on the provider's evaluation.
What does a practical comparison look like?
Imagine a small home-goods shop processing payments at a counter and through an online store. Provider A advertises a low in-person rate but charges separately for online payments, reporting, and a monthly gateway. Provider B has a higher stated rate but includes ecommerce integration and consolidated reports. The better option depends on the shop's actual channel mix and total expected costs—not the first number in an advertisement.
Before deciding, estimate monthly card sales by channel and ask each company to show how its pricing would apply. This is a comparison method, not a universal price benchmark: rates and fees vary by provider, business, card type, and transaction details. Written estimates make important differences easier to spot.
How can you take the next step?
Write down how customers pay today, which tools you need, and the fees or service issues you want to improve. Then compare the complete offer: pricing, payment methods, integrations, security support, funding, and contract terms. A careful review now can help you choose credit card processing services that support a smoother checkout and a more manageable day-to-day operation.
When you are ready to begin, click here to apply. Create a merchant account through the link, then submit your application.