

Welcome — this guide will walk you through upcoming payment technologies and show how your business can prepare to adopt them smoothly. You will learn what modern payment innovations are, why they matter, the main ideas behind them, practical first steps for implementation, mistakes to avoid, and where to go next for deeper learning. No prior technical knowledge is required; the aim is to build your understanding step by step and give you clear, actionable advice.
What is payment technology?
Payment technology refers to methods and tools businesses use to accept money from customers and move funds between accounts. That includes physical devices, like card readers, and digital systems, like online payment gateways or mobile wallets. When we say payment technology advances, we mean emerging systems and improvements such as contactless payments, digital wallets, tokenization for security, cryptocurrencies, biometric payments, and smarter payment platforms powered by data and automation.
Think of payment technology as the plumbing of commerce. Just as water pipes move water reliably from source to sink, payment systems move money from customers to your business. Advances in technology are like upgrading from old, leaky pipes to modern, faster, and more secure piping that also tracks usage and helps you manage flow more efficiently.
Why does it matter?
Upgrading how you accept payments affects nearly every part of your business. Customers expect convenience and security. Faster, safer, and more flexible payment options can increase sales, improve customer satisfaction, reduce fraud, and lower operating costs.
Practical benefits include:
- Higher conversion rates when checkout is easier and faster.
- Better fraud protection through stronger security measures, saving money and reputation.
- Access to new markets and customer segments, such as customers who use digital wallets or cryptocurrencies.
- Reduced friction for repeat customers via stored payment methods and subscriptions.
- Insights from payment data that can inform pricing, marketing, and inventory decisions.
Core concept: Digital wallets and mobile payments
A digital wallet is an app on a phone or watch that stores payment information and lets customers pay without a physical card. Examples include Apple Pay, Google Pay, and Samsung Pay. Mobile payments are when customers use these wallets or apps to complete a purchase.
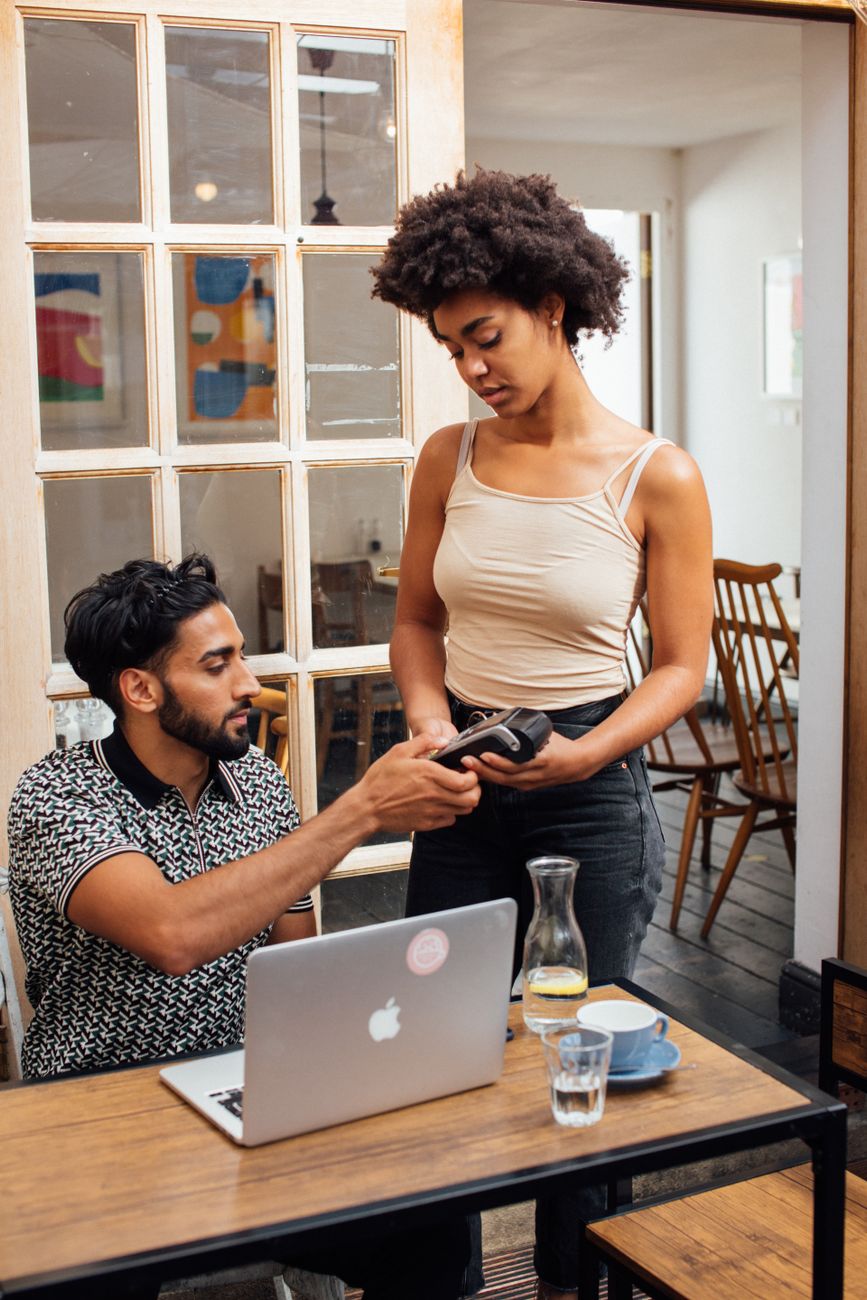
Real-world example: A café customer taps their phone on a terminal and pays instantly without taking out a wallet. For the business, this means faster lines and happier customers.
Why it matters
Digital wallets speed checkout and reduce card-present fraud because the wallet often uses a one-time code instead of a permanent card number.
Core concept: Contactless and NFC payments
Contactless payments use near-field communication, or NFC, a short-range wireless technology, to exchange payment information between a card or device and a terminal. Contactless is familiar in tap-to-pay cards and many mobile wallets.
Analogy: Contactless payment is like handing a receipt through a small slot instead of opening a drawer — it is quicker and keeps the flow going.
Core concept: Tokenization and payment security
Tokenization replaces a real card number with a random string of characters called a token. If a token is stolen, it is useless unless it can be matched to the original transaction system. Tokenization is different from encryption — both protect data, but tokenization specifically substitutes sensitive data with a non-sensitive equivalent.
Example: A customer saves a card to your online store. Instead of storing the actual card number, your payment provider stores a token. If your database is breached, thieves find tokens, not usable card numbers.
Core concept: Payment APIs and integrated platforms
An API, or application programming interface, is a way for software systems to talk to each other. Payment APIs let your website, point-of-sale system, or accounting software connect to payment providers to accept and manage payments automatically.
Analogy: APIs are like electrical outlets. Instead of wiring a custom power system for every appliance, you plug into a standard outlet. Payment APIs let developers plug your systems into payment services with predictable results.
Core concept: Cryptocurrencies and blockchain
Cryptocurrencies are digital currencies that use blockchain, a secure, distributed record of transactions. Accepting crypto can open your business to new customers and offer lower-cost international transfers in some cases.
Plain-language note: Blockchain is like a public ledger that many computers hold copies of; when a transaction happens, the ledger updates in a way that is very hard to change later. That makes it tamper-resistant.
Core concept: Biometric and behavioral payments
Biometric payments use physical traits, such as fingerprints or facial recognition, to authorize transactions. Behavioral payments look at patterns, like typing speed or shopping habits, to detect fraud or speed up authentication.
Example: A customer uses their fingerprint on a terminal to confirm a high-value purchase instead of typing a password.
Core concept: The Internet of Things and embedded payments
The Internet of Things, or IoT, refers to everyday objects connected to the internet. Embedded payments let devices, like a smart vending machine or a connected car, accept payments directly.
Real-world example: A hotel uses smart room sensors that let guests order mini-bar items and have charges added automatically to their room bill.
Core concept: Payment data and AI-driven insights
Modern payment systems capture rich data. When combined with artificial intelligence, or AI, this data can reveal customer trends, detect fraud faster, and automate routine tasks such as reconciliation.
Analogy: Payment data is like footprints on a trail. AI helps you read the footprints to understand where customers came from and where they might go next.
Getting started: First steps for beginners
Start small and be deliberate. Use the following checklist to move from curiosity to a pilot.
- Inventory current systems: List how you accept payments today, including hardware, software, and payment providers.
- Understand customer needs: Ask customers how they prefer to pay. Look at sales data for mobile vs desktop, in-store vs online trends.
- Prioritize use cases: Choose one or two clear improvements that will have the biggest impact, such as enabling contactless payments in-store or adding a digital wallet checkout online.
- Choose flexible providers: Pick payment partners that offer APIs, strong security features, and easy integrations with your existing software.
- Run a pilot: Test a small rollout in one location or with a subset of customers before full deployment.
- Train staff and customers: Make sure team members know how to use new terminals and that customers understand new payment options through signage or short instructions.
- Measure and iterate: Track metrics like checkout time, decline rate, and customer feedback, then improve based on results.
Common mistakes to avoid
- Chasing every trend: Not every new payment method will fit your business. Focus on customer needs and ROI.
- Ignoring security: Skipping proper security practices invites fraud and regulatory headaches. Use tokenization, PCI compliance, and reputable providers.
- Choosing rigid systems: Vendor lock-in makes it hard to change as technology evolves. Favor open APIs and standards when possible.
- Neglecting user experience: A secure system that is hard to use will depress sales. Balance security with convenience.
- Failing to test: Launching broadly without a pilot can create chaos. Test, learn, and scale.
- Overlooking international needs: If you serve global customers, support multiple currencies and international payment methods early on.
Resources and next steps for further learning
Build your knowledge with a mix of vendor documentation, industry guides, and practical learning.
- Payment provider developer docs: Read the integration guides from major providers to understand APIs and capabilities.
- Industry blogs and newsletters: Subscribe to fintech and payments newsletters for trends and case studies.
- Online courses: Look for short courses on payment security, PCI compliance, and API integration fundamentals.
- Local business networks: Talk to peers about what worked and what didn't in real-world deployments.
- Consult a professional: For compliance or complex integrations, a consultant or payments specialist can save time and risk.
Moving forward, adopt a mindset of continuous improvement: pilot one innovation, measure results, and expand the winners. As payment technologies evolve, staying informed and choosing flexible, secure systems will keep your business resilient.
You're ready to start. A simple first action: ask one customer which payment method they prefer and why. Use that feedback to choose a single improvement to pilot this month.