
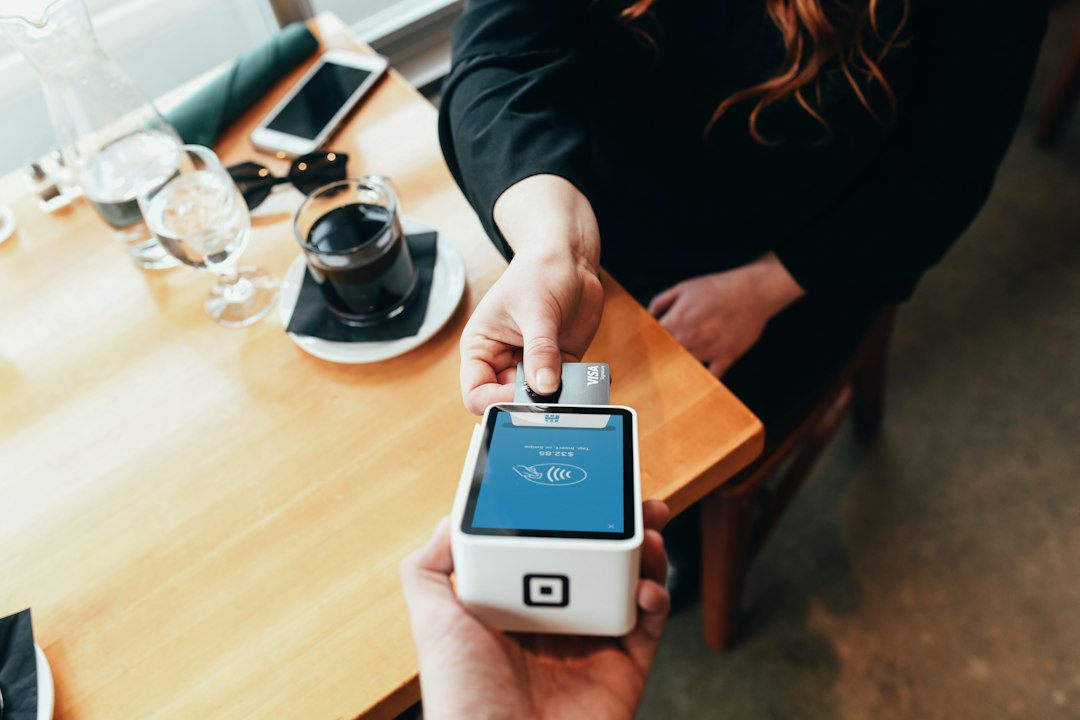

Choosing credit card processing services means finding a secure, reliable way to accept payments without adding unnecessary costs or friction for customers. This guide explains how payment processing works, what fees and features to compare, how to evaluate credit card processing companies, and how to take the next step toward setting up a merchant account.
Key Takeaways
- Compare the full cost of processing, not just the advertised rate.
- Match payment features to how your business sells—in person, online, or both.
- Review security, settlement timing, contract terms, and support before choosing a provider.
How does credit card processing work?
A card payment moves through several parties. A customer taps, inserts, or enters card details; the payment processor sends the transaction through the card network to the issuing bank for authorization. If approved, the transaction is later settled, and funds are deposited into the merchant's account, minus applicable fees.
That process can take seconds at checkout, but the underlying service involves payment gateways, point-of-sale (POS) systems, acquiring banks, card networks, fraud controls, and settlement. The right setup connects these pieces smoothly, so customers can pay conveniently while you can track transactions and reconcile deposits.
Which credit card processing services does your business need?
Start with the way customers actually buy. A retail shop may need a countertop terminal or mobile card reader, while an online business typically needs a payment gateway, hosted checkout, or ecommerce integration. Restaurants, contractors, and service businesses may benefit from invoicing, recurring billing, or payment links.
If you sell through multiple channels, look for tools that bring in-person and online payment reporting together. Useful features may include contactless and digital wallet acceptance, refunds, transaction search, sales reporting, and integration with accounting or inventory software. Choose based on real workflows rather than a long feature list you may never use.
How should you compare processing costs and contract terms?
Ask for a clear breakdown of the complete cost. Pricing may include per-transaction charges, a percentage of the sale, monthly account or gateway fees, equipment costs, chargeback fees, and optional services. The exact amount depends on the provider, transaction type, card mix, and business profile, so compare quotes using your own expected payment patterns.
Also check how pricing is calculated. Some providers use interchange-plus pricing, which separates the underlying interchange and network costs from the processor's markup; others offer tiered or flat-rate pricing. Neither label alone guarantees the lowest total cost. Ask for sample statements or a written estimate, and clarify whether equipment is purchased, rented, or included.
Read the agreement before signing. Confirm the term length, cancellation requirements, renewal conditions, any early termination or equipment fees, and how quickly funds are typically deposited. A transparent provider should explain these details in plain language and identify which charges can change.
What should you look for in a secure payment provider?
Payment security is a business essential, not an optional upgrade. Ask how the provider supports secure card acceptance, protects account access, helps detect suspicious activity, and handles disputes. Use strong passwords and multifactor authentication where available, limit staff permissions, and avoid storing sensitive card data unless you have a necessary, compliant reason.
The Payment Card Industry Security Standards Council explains the PCI DSS requirements for protecting payment account data. Ask prospective providers how their services support your responsibilities, and confirm which steps remain yours. A processor's tools can help, but your business should understand its own security obligations.
How can you evaluate credit card processing companies?
Look beyond the headline rate. Compare the provider's supported payment methods, hardware and software compatibility, settlement and reporting tools, customer support availability, and experience serving businesses like yours. Ask what happens when a transaction is flagged, a deposit is delayed, or a customer disputes a charge.
Reputation matters, but review feedback thoughtfully: look for recurring themes about billing clarity, service responsiveness, and account changes rather than relying on a single review. Before choosing, make sure you can reach support through a channel that works for your business and understand what assistance is included.
Practical context: compare like with like
Imagine a salon that takes payments at the front desk and sends remote invoices for appointments. A quote focused only on in-person transaction rates may miss the cost of online invoice payments, monthly software, or a needed terminal. Comparing the same sales mix, payment methods, and equipment across providers gives a more useful picture than comparing advertised rates alone.
For a simple comparison, estimate monthly card sales by channel, average transaction size, and approximate transaction count. Then ask each provider to show how its fees would apply to those assumptions. Treat the result as an estimate, not a guarantee: actual charges can vary with card types, transaction details, and the agreement.
What is the next step to accepting card payments?
Write down how you sell, which payment methods you need, and the systems you want to connect. Use that checklist to compare providers, request a full fee explanation, and confirm the contract and security details before making a decision.
When you are ready to get started, click here to apply. Create a merchant account through the link, then apply for credit card processing services. Having your business and payment needs clearly outlined will make the application and provider comparison more straightforward.