
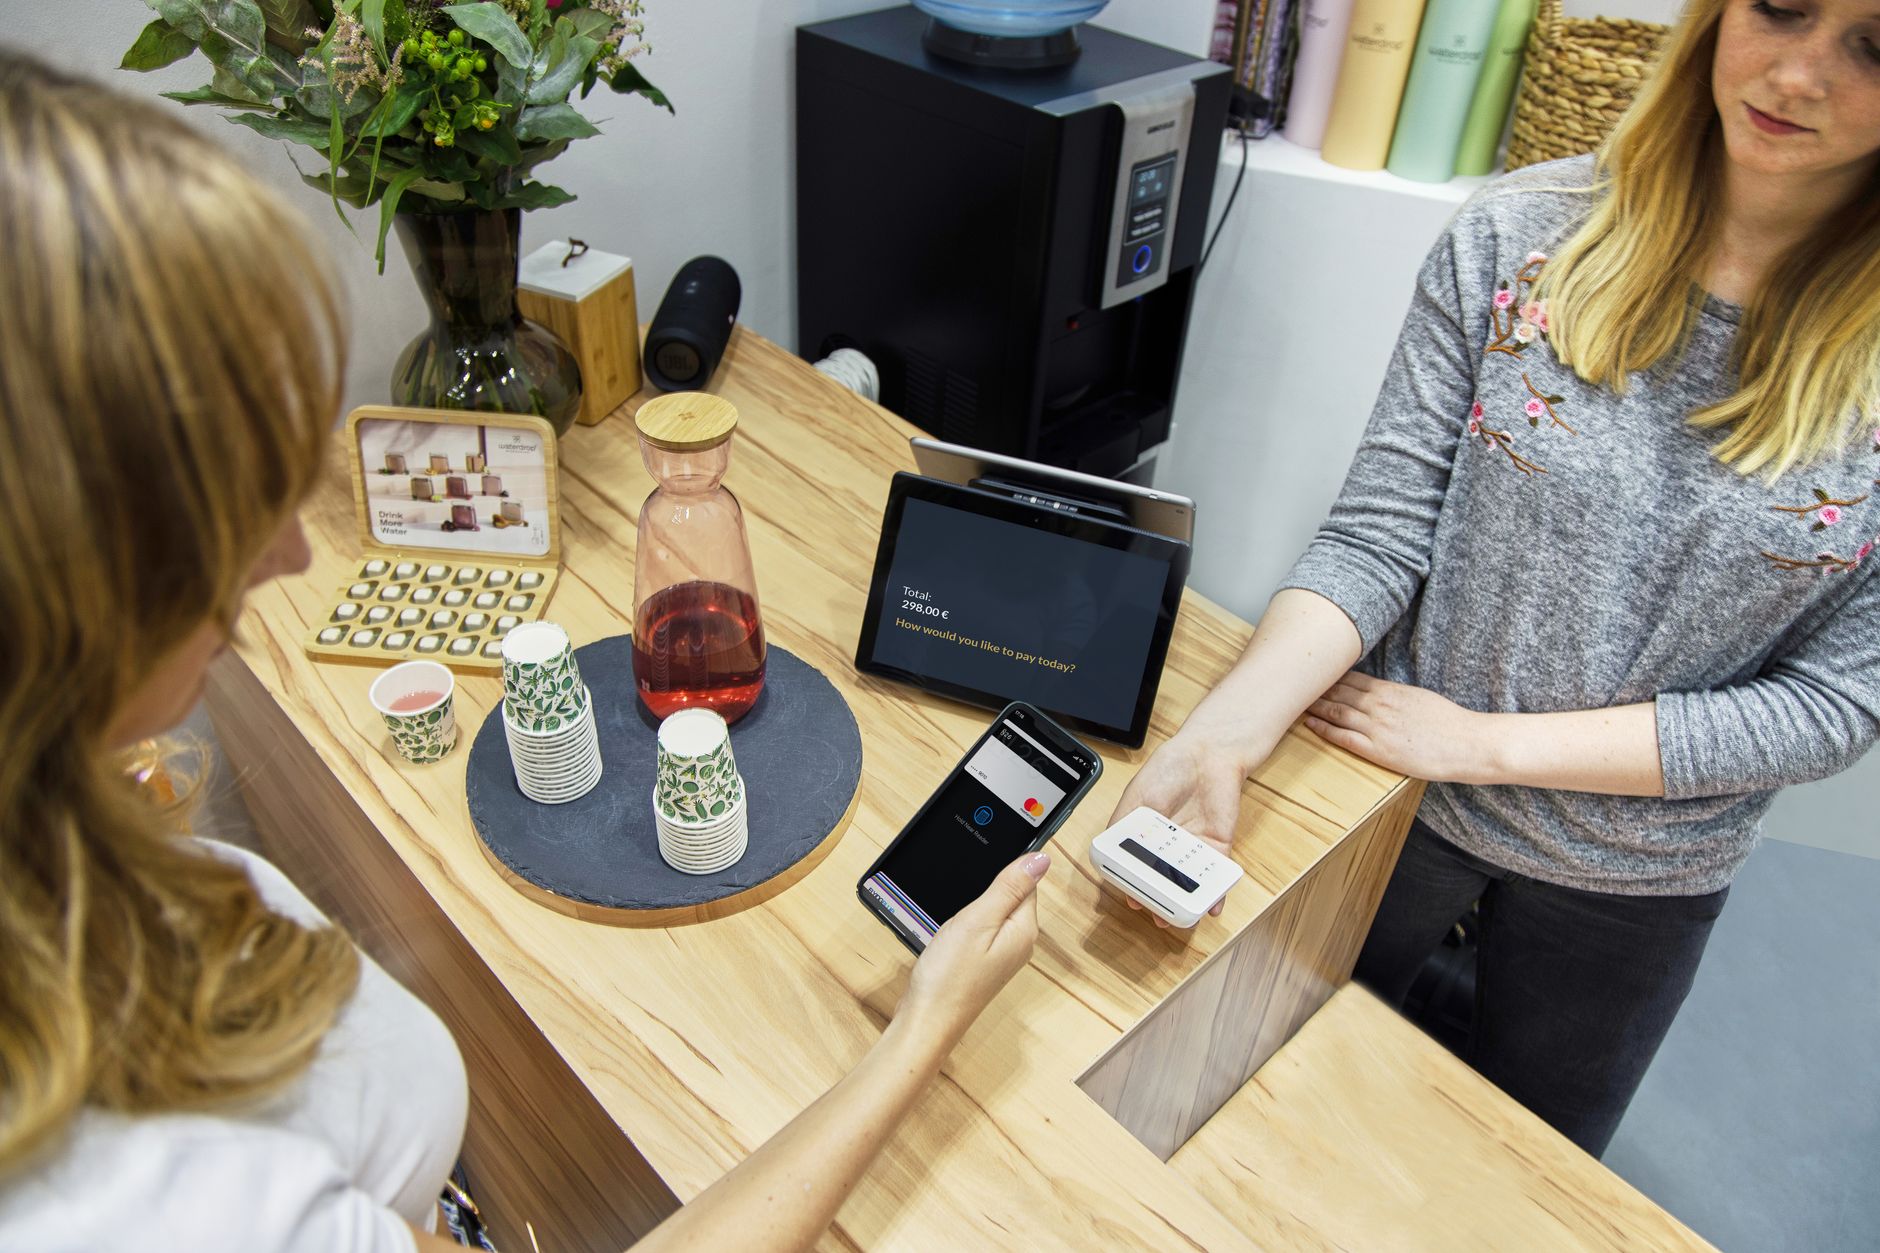

Choosing credit card processing in 2026 means finding a dependable way to accept payments without adding avoidable cost or complexity. This guide explains how credit card processing services work, what fees and features to compare, and how to evaluate credit card processing companies before you apply. Whether you run an online store, a local shop, or a service business, the right setup can make checkout smoother for customers and easier to manage for you.
Key Takeaways
- Compare total processing costs, not just advertised rates.
- Match payment tools to how and where customers buy from you.
- Review security, support, contract terms, and funding timelines before choosing a provider.
How can credit card processing services support your business?
Credit card processing moves a payment from a customer's card or digital wallet through the merchant's payment provider, card network, and issuing bank. The transaction is authorized, settled, and deposited into the business's account, subject to the provider's terms and applicable banking timelines.
For a business owner, the practical value goes beyond accepting a card. A well-matched service may bring together payment terminals, online checkout, invoicing, recurring billing, transaction reporting, and tools for handling refunds. Using connected tools can reduce manual work and help you keep sales records in one place.
Which payment features should you compare first?
Start with your sales channels. A retailer may need a countertop terminal and contactless payments, while a contractor may prioritize mobile payments and digital invoices. An online business should check for website or shopping-cart compatibility, secure checkout, and support for digital wallets.
Then consider how the system fits your daily workflow. Look for clear reporting, simple refunds, user permissions, and responsive customer support. If you bill customers repeatedly, ask whether recurring payments and customer consent management are available. If you sell in person and online, check whether transactions and inventory can be managed across both channels.
How do you compare processing fees and contract terms?
Pricing can include transaction charges, monthly service fees, equipment costs, gateway fees, chargeback fees, and other account charges. The exact mix varies by provider and agreement, so request a written breakdown and ask how costs could change with your sales volume, average ticket size, or payment mix.
Compare the overall cost using your own transaction patterns rather than relying on a headline rate. Also review contract length, cancellation terms, equipment ownership or leasing, funding schedules, and any minimums. Ask what happens if your account is reviewed or a payment is disputed, and how quickly you can reach a person for help.
What security practices matter when accepting payments?
Payment security is a shared responsibility. Use providers that explain how they protect payment data, support secure authentication, and help merchants follow relevant card-industry requirements. Avoid storing sensitive card information yourself unless you have the expertise and infrastructure to do so securely.
The PCI Security Standards Council provides the official overview of PCI DSS requirements, the payment card industry's baseline standard for protecting account data. Ask prospective providers what security features are included and what actions remain your responsibility, such as securing devices, limiting staff access, and maintaining strong passwords.
What should you look for in credit card processing companies?
Look beyond promotional claims. Evaluate the provider's payment methods, integrations, customer support, reporting, and ability to serve your industry. Confirm that the company can support your current business model and likely next steps, such as adding online sales or opening another location.
Read the service agreement carefully and get answers in writing when details are unclear. Check how disputes are handled, which transactions may trigger additional review, and whether the provider offers guidance during onboarding. A clear explanation is a useful sign that you understand the relationship before accepting payments.
What does a real-world cost comparison look like?
Consider a small café that accepts payments at a counter and through online orders. It should compare the costs and capabilities for both in-person and online transactions, including terminal expenses, gateway charges, refunds, and funding timelines. A low advertised rate may not be the least expensive option once monthly fees and the café's actual payment mix are included.
There is no single fee estimate that applies to every merchant. Pricing depends on provider terms, card type, transaction method, business risk, and other factors. Use recent sales records to request a tailored estimate, then compare the same assumptions across providers.
How can you get started with a merchant account?
Prepare basic business details, expected sales volume, the ways you plan to accept payments, and any website or point-of-sale requirements. Having this information ready makes it easier to assess available options and complete an application accurately. Review the provider's terms and confirm that the proposed setup matches your needs before proceeding.
To take the next step, create a merchant account through the application page. After creating your account, you can apply: click here to apply. Compare the features and terms carefully, and choose a credit card processing setup that makes payments straightforward for both your customers and your team.