
Choosing credit card processing affects how customers pay, how quickly transactions settle, and what a business pays in fees. This guide explains what to compare when selecting a payment processor, what questions to ask before signing, and how Mr. Truby's more than 20 years in payment processing may help business owners assess their options. To discuss accepting credit cards for your business, call 928-706-6769 or visit the page linked with this article.
What should a business compare when choosing credit card processing?
Start by identifying your actual payment channels: in-person checkout, online sales, invoices, recurring billing, or a combination. A processor should support the way your business operates, rather than require workarounds that slow checkout or complicate reconciliation.
Next, examine the full fee structure. Processing costs may include interchange, processor markups, per-transaction charges, monthly account fees, equipment costs, gateway fees, and optional services. Request a written breakdown and ask how fees could change with transaction volume, card type, or sales channel.
How do payment methods and equipment affect daily operations?
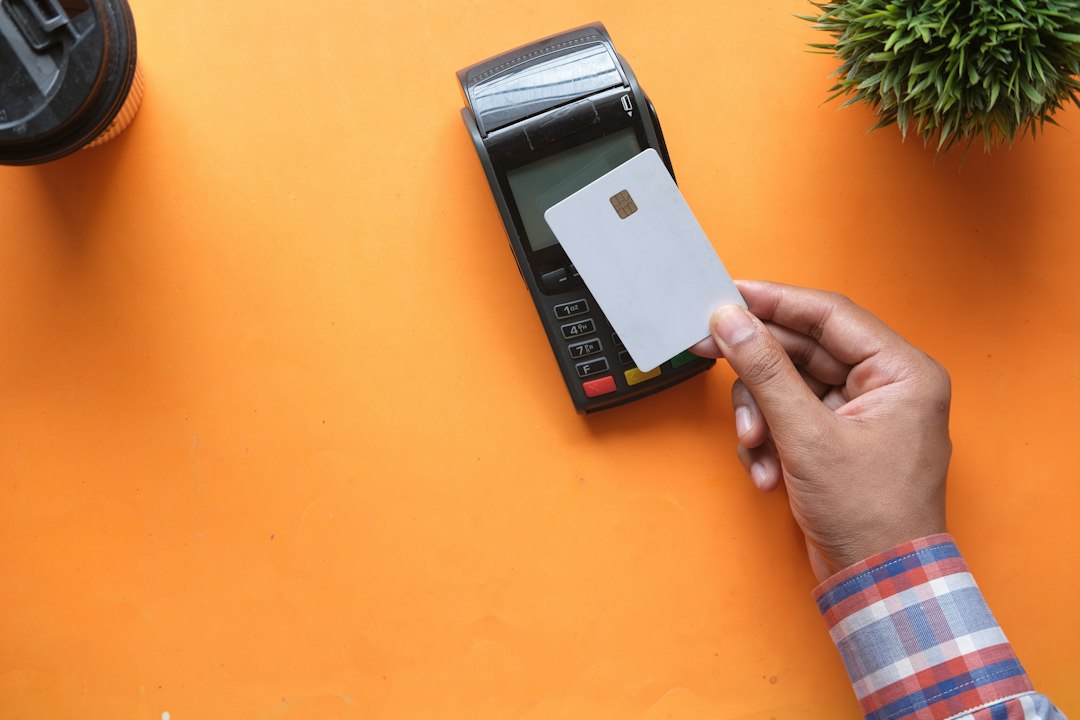
For a storefront, check whether the point-of-sale terminal supports chip cards and contactless payments, including mobile wallets. For online transactions, ask whether the payment gateway integrates with your website or ecommerce platform and what tools it provides for refunds, recurring payments, and transaction reporting.
Equipment and software should fit your team's workflow. Confirm who supplies and supports terminals, whether devices are leased or purchased, and what happens if equipment fails. If staff need to manage payments across locations, verify that reporting and user permissions meet those needs.
Which contract and service details deserve close attention?
Before signing, read the agreement for contract length, cancellation terms, early termination fees, automatic renewal language, and any minimum monthly charges. Ask how funds are deposited, which bank account is required, and what circumstances can delay a payout or trigger a reserve review.
Clarify how the provider handles disputes and chargebacks. Find out where to access transaction records, what evidence is needed for a response, and how quickly you can reach support. A low quoted rate may not be useful if the service lacks clear pricing or practical assistance when a payment issue disrupts business.
How can a business reduce payment risk?
Payment security is a shared responsibility between the merchant, processor, and other service providers. Ask which security controls are included, how access is managed, and what steps are required to protect cardholder information. Avoid storing sensitive card data unless your systems and procedures are designed to do so safely.
The PCI Security Standards Council explains the PCI DSS payment card security responsibilities for merchants. Use that guidance as a starting point, then confirm with your processor what applies to your particular payment setup. No single tool eliminates fraud or security obligations.
What experience and service questions should you ask?
Experience can help a representative understand common payment setups, but it does not replace transparent terms or a suitable product. Ask the provider to explain the pricing in plain language, identify potential add-on costs, and show how the proposed system would handle a typical sale, refund, and end-of-day reconciliation for your business.
Useful context comes from your own transaction records. For example, a restaurant may need fast counter service and reliable terminal support, while a consultant may prioritize online invoices and recurring billing. Reviewing a recent processing statement, average transaction size, monthly volume, and refund patterns can make a quote more relevant. These are business-specific inputs, not a guarantee of a particular rate or savings.
How can Mr. Truby help you explore payment processing?
Mr. Truby has been in payment processing for more than 20 years and welcomes conversations with business owners who need to accept credit cards. That experience may offer a useful starting point for discussing payment channels, equipment, pricing questions, and service expectations. As with any provider, ask for the applicable terms in writing and compare them with your current setup.
If your business is evaluating credit card processing, prepare a recent statement and a short list of needs before reaching out. Call Mr. Truby at 928-706-6769 or go to the page associated with this article to discuss options for your business.