
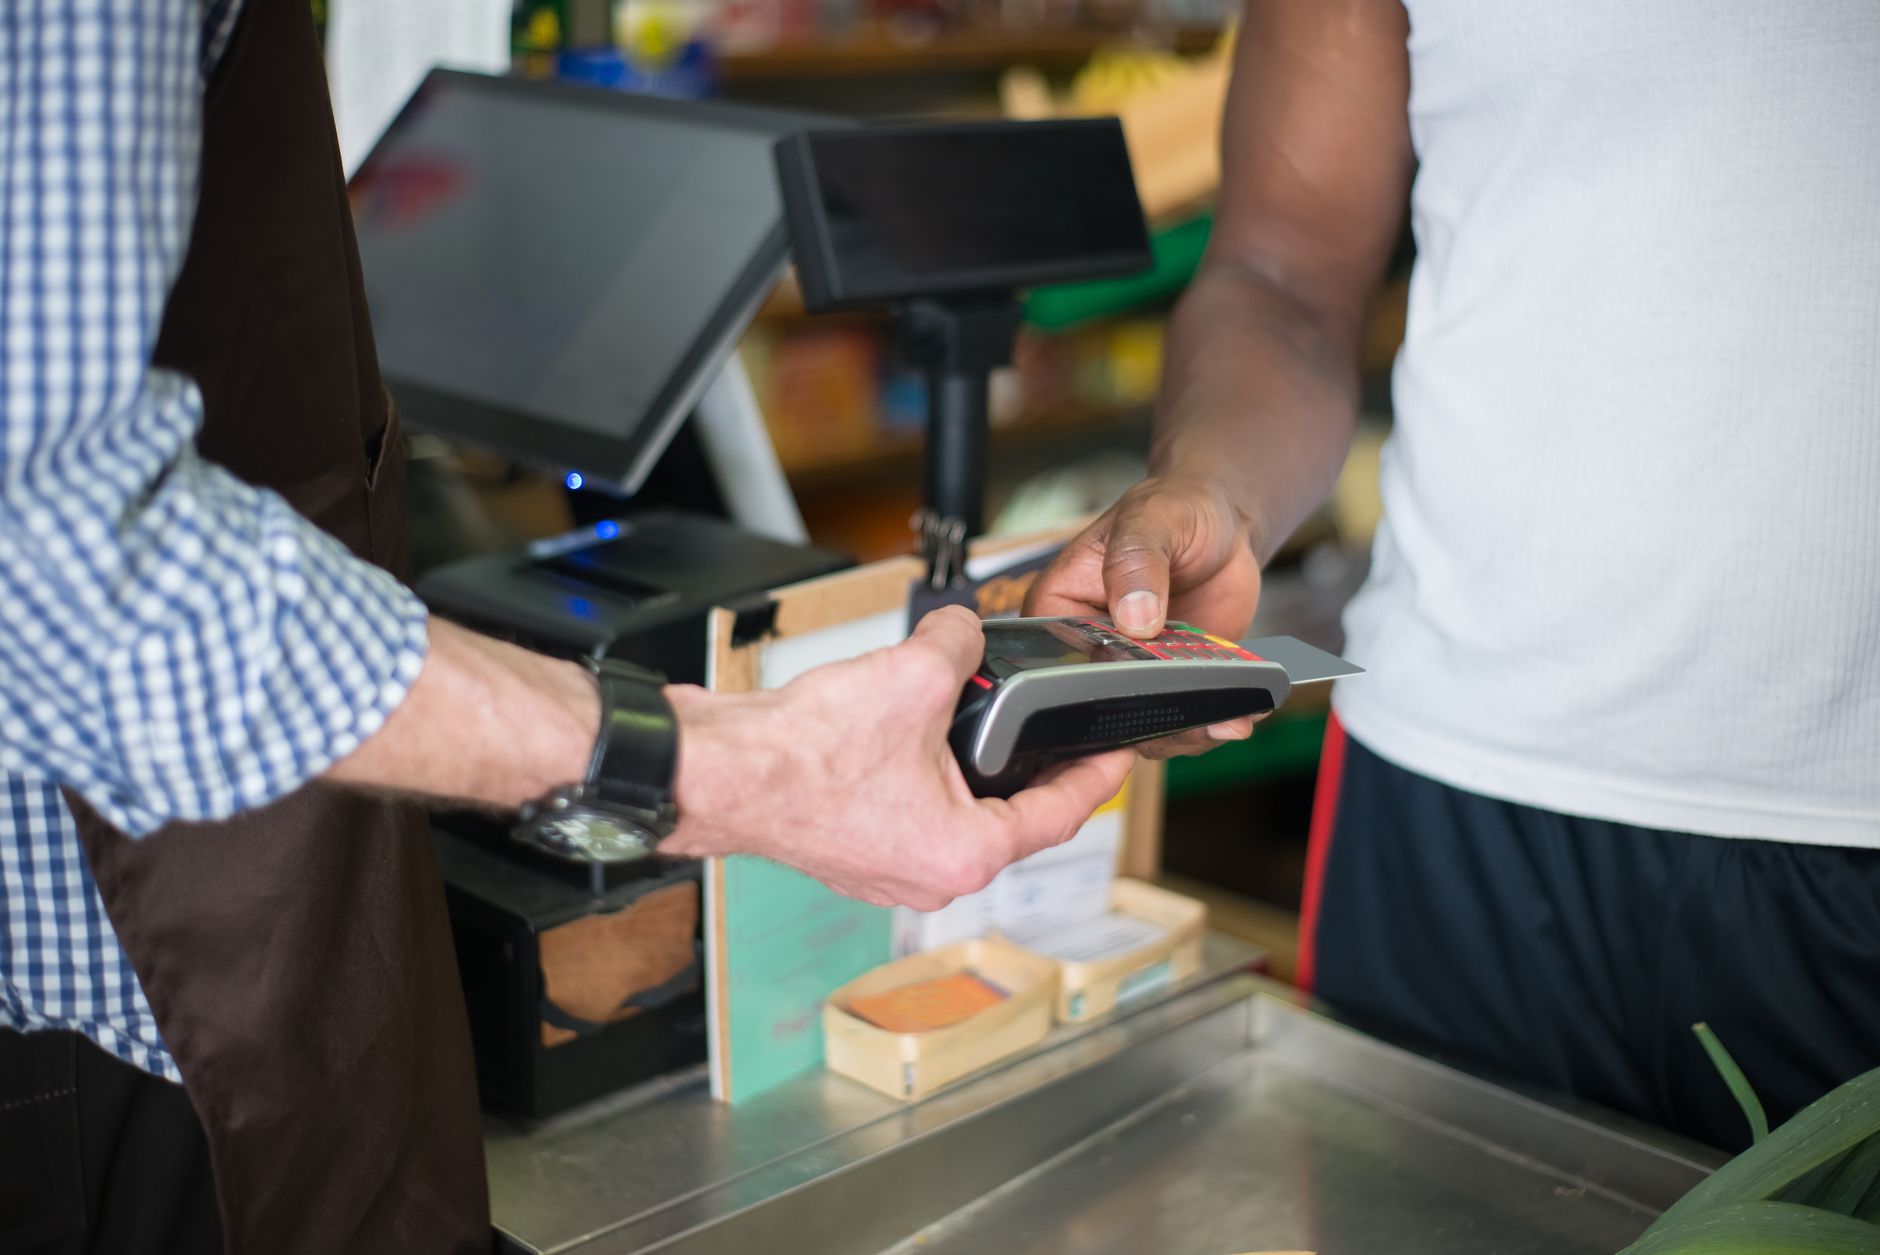

Accepting credit cards can make it easier for customers to pay, but choosing a payment-processing provider is not simply a matter of picking the first option that appears in a search. Fees, equipment, transaction workflows, and support all affect the experience. For business owners comparing credit card processing, Mr. Truby brings more than 20 years of experience in payment processing and invites businesses that need to accept cards to call 928-706-6769 or visit this application page.
The practical question is not whether card acceptance is useful; for many businesses, it is an expected part of serving customers. The more important question is whether a proposed setup fits the way the business operates. A careful review can help owners ask better questions before committing to a payment solution.
Why Credit Card Processing Deserves a Closer Look
Payment processing sits at the intersection of customer service, cash flow, and business operations. A customer may pay in person, online, over the phone, or through an invoice link, and each channel can require different tools and procedures. The right arrangement should make those transactions manageable without adding unnecessary complexity.
Costs also deserve close attention. Processing statements may include several types of charges, and the total cost depends on factors such as transaction volume, card type, sales channel, and pricing structure. Comparing providers on a single advertised rate can therefore produce a misleading picture.
Service matters as well. When a terminal stops working or a payment is delayed, a business needs a clear route to assistance. Evaluating support before a problem occurs is a more disciplined approach than treating it as an afterthought.
What to Evaluate in a Payment Processing Provider
Start by describing how customers currently pay and how you would like them to pay in the future. A retailer with a staffed counter may prioritize a dependable point-of-sale terminal, while a consultant may need online invoices and payment links. Restaurants, mobile service providers, and ecommerce businesses may have distinct requirements of their own.
Ask a provider to explain the proposed setup in terms that match your daily workflow. Which devices or software are involved? How are refunds handled? How do transactions appear in reports, and how are funds transferred to the business bank account? Clear answers make it easier to compare a service with actual operational needs.
Pricing, Fees, and Contract Terms
Request a full explanation of pricing rather than relying on a headline rate. Ask about transaction charges, monthly or account fees, equipment costs, and any other costs that may apply. The exact terms vary by provider and business, so review the agreement and current pricing in writing before making a decision.
It is equally important to understand the contract. Check whether there is a term commitment, what happens if you change providers, and whether equipment is purchased, leased, or supplied under other conditions. If a term is unclear, ask for clarification before signing.
Equipment and Sales Channels
Businesses that accept payments in person may need a countertop terminal, a mobile reader, or an integrated point-of-sale system. Online sellers may need a payment gateway that works with their website or ecommerce platform. Some businesses need more than one channel, which makes compatibility a key part of the conversation.
Consider how staff will use the equipment, too. A solution should be practical for the people processing transactions and understandable for customers. Ask whether training, setup guidance, and technical support are available, and confirm which devices or integrations are included in the proposed arrangement.
How an Experienced Payment Processing Contact Can Help
Payment processing has many moving parts, and business owners may not have time to investigate every provider and technical detail on their own. An experienced contact can help organize the discussion around the business's transaction patterns, preferred sales channels, and service expectations. That guidance is most useful when it is specific, transparent, and based on the owner's needs rather than a generic pitch.
Mr. Truby has been in payment processing for over 20 years. For an owner who wants to discuss accepting credit cards, that experience may provide a starting point for asking informed questions about available options. It does not replace reviewing the terms, comparing the costs, or confirming that a particular service fits the business.
Business owners can reach Mr. Truby at 928-706-6769 or begin through the online application page. Before contacting any provider, it can help to prepare a recent processing statement, an estimate of monthly sales, and a short list of the ways customers need to pay.
Questions to Ask Before You Accept Credit Cards
A productive conversation should clarify both the service and the costs. Ask how the pricing is structured, which fees may appear, and how the provider explains changes or exceptions. Request documentation that lets you review the terms at your own pace.
Then focus on operations. Ask which payment channels are supported, whether your existing point-of-sale or ecommerce tools can be used, and what assistance is available if a device or transaction process fails. If your business has seasonal peaks or unusual transaction patterns, explain those details rather than assuming a standard package will suit them.
Finally, ask how to evaluate the proposal against your current arrangement. A side-by-side comparison of total costs, equipment, features, and support is more useful than a comparison based on a single percentage. It also gives you a clearer record of why you selected a particular solution.
Matching Credit Card Acceptance to Your Business
The best payment setup depends on the business model. A shop that serves customers face to face may value fast checkout and reliable terminals. A contractor may prioritize taking payment on location, while a professional service firm may want to collect invoices online. Ecommerce operators, in turn, need to consider how payments connect with their website and order-management process.
Customer expectations should inform the decision, but they should not be the only factor. A new payment channel can improve convenience while also introducing costs, hardware needs, or additional procedures. Consider whether the expected benefit justifies the operational and financial commitments.
Security and responsible handling of payment information also belong in the evaluation. Ask what steps the provider and any connected systems require to protect payment data, and follow applicable guidance for your business. Do not assume that a particular feature or service guarantees compliance; confirm responsibilities and requirements directly with qualified sources.
A Straightforward Process for Comparing Providers
First, document your current needs: where payments happen, how often they occur, what equipment is in use, and which staff members handle transactions. This gives providers a consistent picture and reduces the chance of comparing proposals built on different assumptions.
Next, collect written proposals and examine the details. Compare expected costs using realistic transaction patterns, not just a best-case estimate. Review the contract, equipment arrangement, supported sales channels, reporting tools, and customer support options together.
After that, identify any unresolved questions before you enroll. Clarify vague pricing, unfamiliar terms, and compatibility concerns. A provider should be able to explain the offer clearly enough for you to make an informed choice without pressure.
Take the Next Step Toward Card Acceptance
For a business that is ready to accept credit cards—or wants to reassess an existing setup—the most useful first step is a focused conversation about actual payment needs. Consider your sales channels, transaction volume, equipment, and service expectations, then use that information to evaluate the available options.
Mr. Truby has more than 20 years in payment processing and is available to speak with business owners who need to accept credit cards. Call 928-706-6769 or visit https://www.appsubmit.com/?source=44828.1 to get started, and review all pricing and terms carefully before choosing a payment-processing solution.