

Customers may discover a product on a website, ask a question by phone, and complete their purchase in a store. They expect paying to be just as easy wherever they choose to shop. For a business, making that happen across retail, online, and phone channels takes more than offering several ways to pay. The channels need to work together.
This beginner's guide explains what multi-channel payment acceptance means, why it matters, and how its essential parts fit together. You'll learn how to get started, protect customer information, avoid common mistakes, and choose practical next steps. You do not need a payments background: we'll build from the basics and use familiar examples along the way.
What Is Multi-Channel Payment Acceptance?
Multi-channel payment acceptance is the ability to take payments through different ways of shopping while giving customers a consistent, dependable experience. Common channels include in-person retail, an online store or app, and phone orders handled by staff.
Think of each channel as a door into the same shop. A customer might enter through the front door, the website, or a phone call. Behind those doors, the business still needs to know what was purchased, whether payment succeeded, and how to handle a refund or question. When the channels operate separately, staff may have to piece together the answer from different systems. When they are coordinated, the experience feels more connected.
Multi-channel does not necessarily mean that every payment is processed in exactly the same way. A shopper may tap a card at a counter, enter card details online, or pay through a secure link after calling. The goal is to make each route convenient and secure, while keeping important information and processes aligned.
Why Does It Matter?
Customers choose the channel that suits their situation. Someone in a hurry may prefer contactless payment at a store. Another customer may want to browse online late at night, while someone else may call to order a product that is difficult to choose without advice. Offering suitable payment options makes it easier for each person to complete a purchase.
- Better customer experience: Clear, familiar payment steps reduce uncertainty and unnecessary effort.
- More ways to complete a sale: A convenient alternative can help when a customer cannot or does not want to use the first payment method offered.
- More consistent service: Connected processes can help staff answer questions about orders, payments, and refunds across channels.
- Fewer manual tasks: A well-planned setup can reduce repeated data entry, paper records, and time spent reconciling separate reports.
- Improved oversight: A clearer view of transactions can help owners understand sales patterns and spot issues that need attention.
These benefits are not automatic. Adding a new channel without planning can create extra work or confusion. The aim is not to offer every possible payment method; it is to make the methods customers need work smoothly and responsibly.
Core Concept: The Three Main Payment Channels
Each channel has different practical needs, even when the customer is buying the same item.
In-person retail
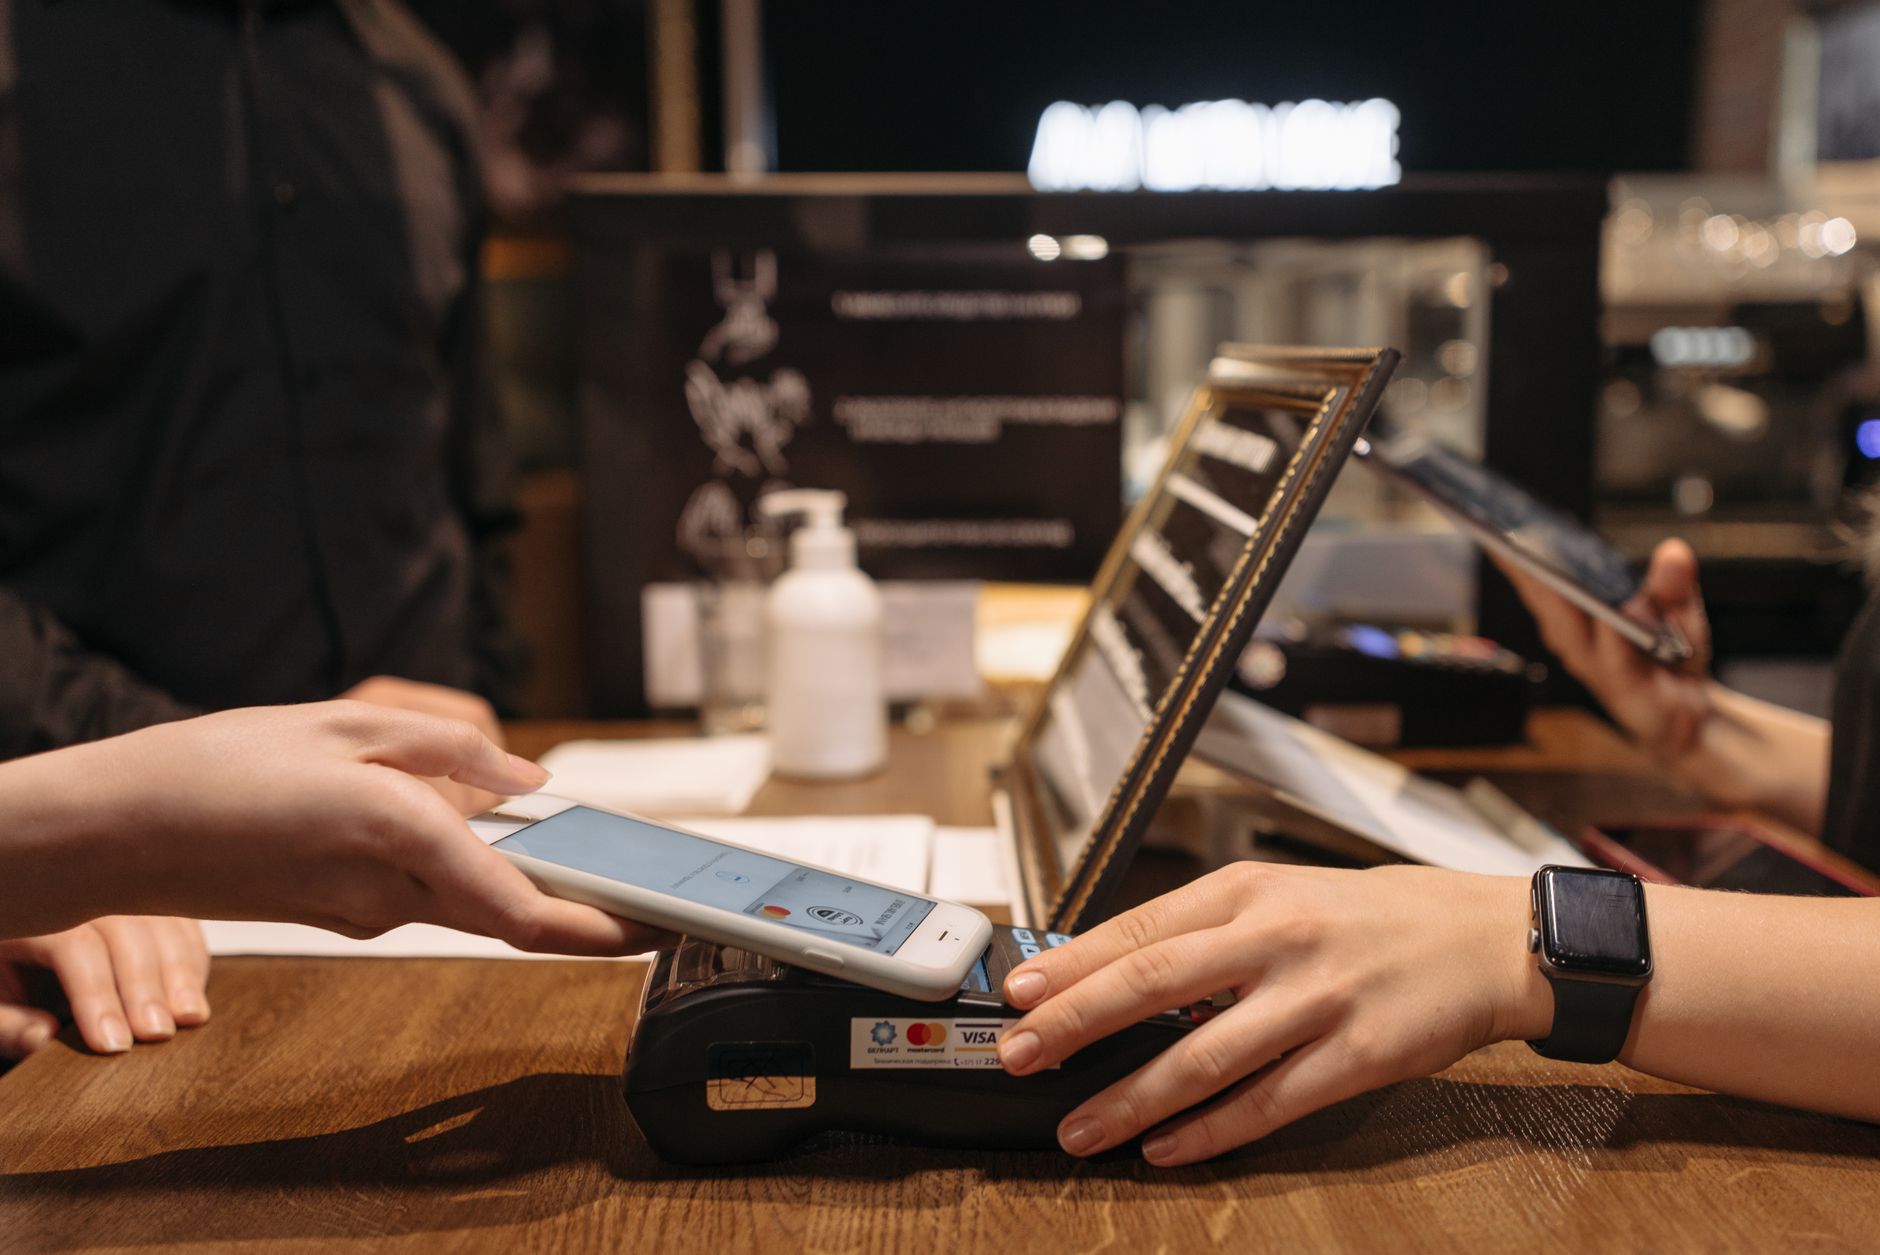
In a shop, a payment terminal reads or accepts a customer's card or mobile wallet. Customers may insert a chip card, tap to pay, or use another supported method. The terminal should be easy to use, placed where customers can see the total, and connected reliably to the payment service. Staff should know what to do if a payment is declined or the terminal loses its connection.
Online payments
In an online checkout, customers typically enter payment information or choose a supported digital wallet. A good checkout explains the total, delivery costs, and next steps before the customer submits the order. It should work well on a phone as well as a computer. Too many fields, unclear error messages, or unexpected charges can make people abandon a purchase.
Phone orders
Some customers place orders with a staff member over the phone. Because payment details are being shared verbally, the process requires particular care. Staff should follow approved procedures and use a secure payment solution designed for phone transactions. Avoid writing card numbers on paper or storing them in notes, email, or customer-service records. Where appropriate, a secure payment link can let the customer enter details themselves.
Across all three channels, make it clear what the customer is paying for and how they will receive confirmation. Small details—such as a clear receipt and an accurate order reference—make support easier later.
Core Concept: A Connected View of the Customer and Order
Customers often think of a business as one organization, even when its store, website, and phone team use different tools. A connected payment setup helps staff see the information they need without asking customers to repeat themselves.
For example, imagine a customer orders a jacket online and calls the next day to ask about delivery. If the phone team can locate the order and see its payment status, they can help quickly. If the order exists only in a separate system the team cannot access, the customer may have to search for confirmation details or call again.
Connection does not require every system to be replaced or every team to see every piece of information. It means choosing sensible ways for essential records—such as order number, amount, status, and refund progress—to be available to authorized staff. Start by mapping how information moves today, then identify the gaps that cause repeated work or customer frustration.
Core Concept: Payment Processing and Fees
When a customer pays by card, several organizations and systems may help move the payment from the customer's account to the business. A payment processor is a service that helps send transaction information for approval and settlement. Settlement is the process of transferring approved funds to the business's account, subject to the provider's timing and terms.
Providers may charge fees for processing payments. The amounts and structure vary, and may depend on the payment method, channel, transaction, or agreement. A low advertised rate does not always mean the lowest overall cost if other charges or service limitations apply. Compare pricing in writing and ask what is included, such as equipment, support, refunds, chargebacks, and access to transaction reports.
Keep the customer experience in view when comparing costs. A payment option that saves a small amount per transaction may not be a good choice if it creates unnecessary friction or fails to meet customer needs. At the same time, avoid paying for features your business will not use.
Core Concept: Security and Customer Trust
Payment information is sensitive, so protecting it is essential to customer trust. A practical starting point is to limit who can access payment-related systems, use strong unique passwords, turn on extra sign-in verification when available, and keep devices and software up to date.
Choose established payment services that explain their security responsibilities and provide tools appropriate to each channel. Do not collect or keep card details unless there is a clear, approved business need and a secure process for doing so. For phone orders, train staff on how to handle spoken information. For online payments, use a properly secured checkout and avoid sending sensitive payment details through ordinary email or text messages.
Rules and security obligations depend on location, business type, and the way payments are handled. Ask your payment provider or a qualified adviser what applies to your business. If you suspect a security incident, follow your provider's reporting process promptly and avoid making promises about the cause or impact before it has been investigated.
Core Concept: A Consistent Experience Across Channels
Consistency is not about making a store counter look like a website. It is about making the important parts of paying feel predictable. Customers should be able to understand the total, recognize the business, know whether a transaction succeeded, and find help if something goes wrong.
Use clear language for payment instructions, confirmation messages, and refund policies. Make sure staff know where to direct customers who need assistance. If the online and in-store returns process differs, explain the difference before purchase rather than surprising customers later.
Accessibility matters, too. Use readable text, straightforward instructions, and payment options that work for a range of customers. Test the experience on common devices and ask people unfamiliar with the process to try it. Their questions can reveal confusing steps that are easy for the business to overlook.
Getting Started: First Steps for Beginners
- Map how customers pay today. List your locations, website or app, and phone-order process. Note which payment methods each channel accepts and who handles questions or refunds.
- Ask customers and staff where the friction is. Look for repeated complaints, abandoned online orders, slow checkout steps, confusing receipts, or time-consuming manual work. Use real observations rather than assumptions.
- Set a few clear goals. You might want to reduce checkout delays, make phone orders safer, simplify reconciliation, or help staff find order information faster. Specific goals make it easier to compare solutions.
- Compare providers and tools. Ask about channel support, setup costs, transaction fees, reporting, refunds, customer service, security features, and how the tools work with your existing systems. Confirm any promises in writing.
- Plan the customer and staff experience. Write down what customers will see and what staff should do when payments are approved, declined, refunded, or interrupted by a connection problem.
- Test before a full rollout. Try realistic purchases and refunds in each channel. Check receipts, order records, reporting, and what happens when something fails. Train staff and gather feedback before expanding.
- Review results regularly. Check whether the new process is meeting your goals. Track useful indicators, such as payment completion, customer questions, processing costs, and time spent on administrative tasks.
Small businesses can begin with one improvement rather than changing everything at once. For instance, you might first make the online checkout clearer, then improve the phone-order procedure, and later connect reporting across channels.
Common Mistakes to Avoid
- Choosing a provider on price alone: Compare the full cost, service, supported channels, and fit with your business—not just one advertised rate.
- Treating every channel as a separate business: Disconnected records can make support, refunds, and reporting harder. Plan how essential order information will be found.
- Collecting payment details insecurely: Do not leave card numbers in paper notes, email, chat, or unprotected files. Use approved tools and procedures.
- Skipping staff training: Even a capable system can create poor service if employees do not know how to use it or respond to a failed payment.
- Ignoring refunds and exceptions: Test what happens when a customer changes an order, a payment is declined, or a refund is needed—not just a successful purchase.
- Adding too many options without a reason: Extra choices can complicate checkout and operations. Prioritize methods customers actually use and your business can support well.
- Failing to test on real devices: A checkout that looks fine on a desktop may be difficult on a small phone screen. Test the channels your customers use.
Resources and Next Steps for Further Learning
Begin with your current payment provider's documentation and support team. Ask for plain-language explanations of fees, security responsibilities, settlement timing, refunds, and reporting. If you are considering a new system, compare more than one provider and request a demonstration using scenarios from your business.
For security guidance, consult recognized payment-industry resources and the relevant authorities in your region. Your accountant or bookkeeper can help you understand how transaction records fit into your accounting process. Industry groups, small-business support organizations, and practical training for staff can also help you build confidence.
Keep learning from your own customers. A short conversation with staff, a review of common support questions, or a simple test of your checkout can show where to focus next. You do not have to build a perfect system in one day. Start by writing down every way a customer can pay today, then choose one small friction point to improve this week.