
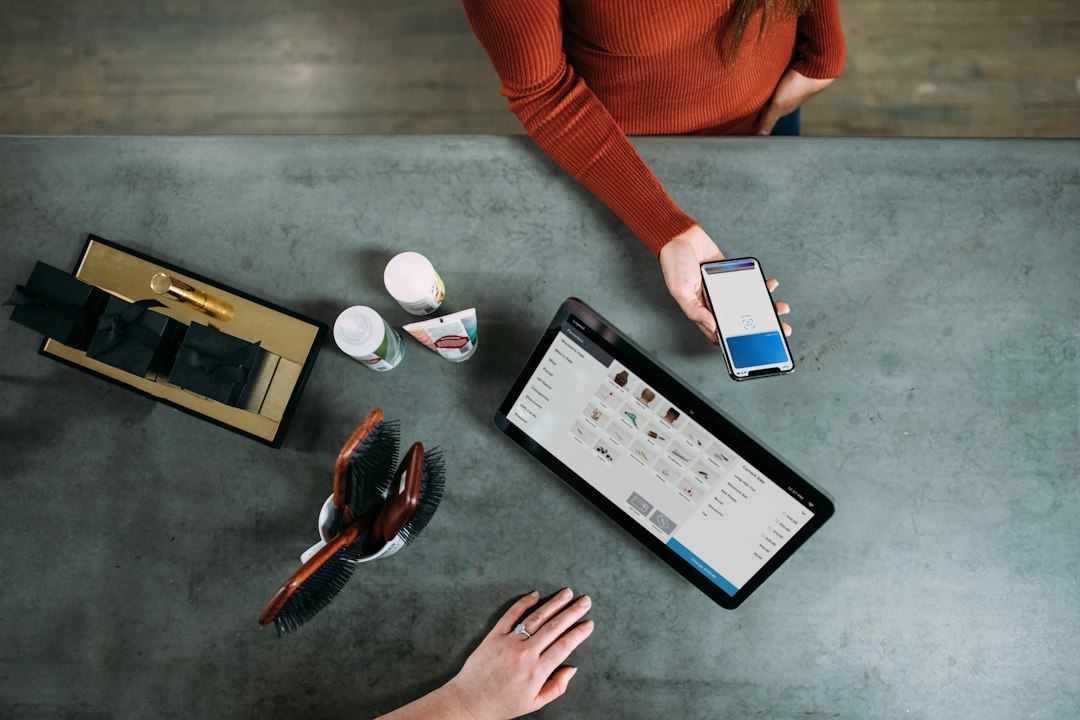

Choosing credit card processing services means finding a reliable way to accept payments, protect customer data, and get funds into your business account. This guide explains how credit card processing works, what to compare among credit card processing companies, and how to choose a setup that fits your sales channels and budget. Whether you sell in person, online, or both, the right provider can make checkout smoother for you and your customers.
Key Takeaways
- Compare total processing costs, not just the advertised transaction rate.
- Match payment tools to how you sell: in person, online, by invoice, or across channels.
- Review security, funding timelines, support, and contract terms before applying.
What happens when a customer pays by card?
Credit card processing moves payment information between the customer, merchant, payment processor, card network, and issuing bank. The transaction is authorized or declined, then approved funds are settled and deposited according to the provider's schedule. A payment gateway typically supports online transactions, while a point-of-sale (POS) terminal accepts card payments in person.
These steps happen quickly, but each part matters. A dependable system helps prevent avoidable checkout delays, records sales accurately, and gives you tools to manage refunds, disputes, and reconciliations.
Which credit card processing services does your business need?
Start with the ways customers currently pay—and how you expect them to pay next year. A neighborhood shop may need a countertop terminal and contactless payments; an online retailer may need a hosted checkout, gateway, and integrations with its store platform. Service businesses often benefit from invoicing or payment links, while mobile sellers need portable, connected hardware.
Look for a provider that can support your sales channels without making everyday tasks complicated. Useful features may include a virtual terminal for keyed payments, recurring billing, digital receipts, reporting, and integrations with accounting or inventory software. Ask whether hardware, software, or gateway access carries separate fees.
How can you compare processing costs accurately?
Rates are only one part of the cost. Review the full pricing schedule for transaction fees, monthly charges, PCI-related fees, equipment costs, chargeback fees, and any minimums or cancellation terms. Pricing may also vary by card type, transaction method, and the provider's pricing model, so compare estimates using your own sales mix.
For example, an in-person business that takes mostly chip or contactless payments has different needs from an online store that handles card-not-present transactions. Request a written breakdown based on your average ticket, monthly volume, and payment channels. If a quote is unclear, ask the company to explain every line item before you commit.
What should you check before choosing a provider?
Evaluate credit card processing companies on more than price. Confirm which payment methods they support, when deposits typically arrive, and how customer support is reached during a payment issue. Check whether the provider offers useful transaction reporting and whether its tools integrate with your existing systems.
Security deserves equal attention. Ask how the service supports secure handling of card data, what steps you need to take to meet your responsibilities, and how suspicious activity or disputes are managed. The PCI Security Standards Council's guidance for merchants on payment card security explains why businesses that accept cards must consider their role in protecting payment information.
What does a good payment setup look like in practice?
Consider a small retailer taking payments at a store and through an online shop. A connected POS and e-commerce setup can help keep sales records organized, while consistent reporting makes it easier to review transactions and refunds. The owner should still confirm that the systems actually integrate and understand whether each channel has different pricing or funding timing.
For a service provider, invoices and payment links may make it easier for customers to pay remotely. In either case, the best fit is the one that supports the business's actual workflow—not a long feature list that adds cost without solving a real need. Ask for a clear explanation of onboarding, equipment, support, and settlement before moving forward.
How do you get started with a merchant account?
Gather basic business details, estimate monthly card sales, and decide which channels and payment methods you need. Then review the application and service terms carefully, including pricing, equipment requirements, and any contract conditions. Accurate information can help the provider assess your account and recommend a suitable setup.
Ready to take the next step? Click here to apply. You can create a merchant account from that page; create an account first, then submit your application. Before you begin, have your business information ready and make sure the available services match how you plan to accept payments.