
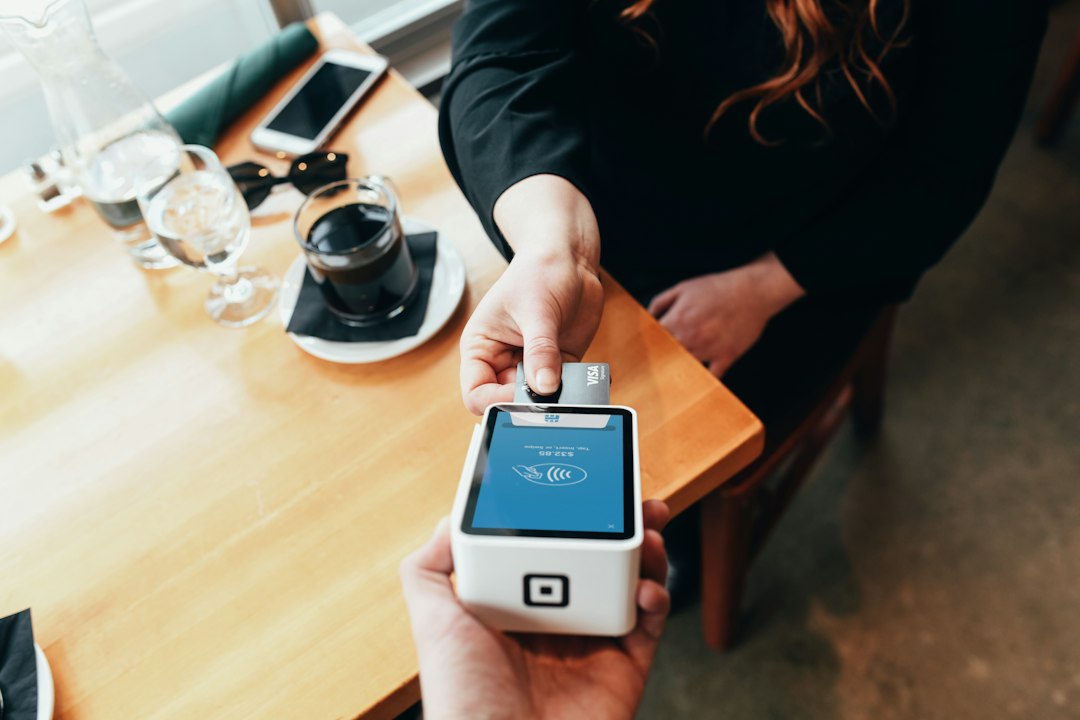

Payment processing can be one of those business expenses that seems small with each sale but adds up over time. The good news is that thoughtful choices about payment technology, pricing, and daily practices can help reduce costs without making checkout harder for customers. This guide explains the basics of payment processing, why efficiency matters, and ten practical recommendations you can use to get started—even if you have never managed payment systems before.
What Is Payment Processing?
Payment processing is the set of steps that moves money from a customer's payment method to your business account. When someone pays by card or digital wallet, a payment processor securely passes information between the customer's bank, the card network, and your bank. It checks whether the payment is approved and helps arrange the transfer of funds.
Think of a processor as a trusted courier: it carries payment information to the right places, checks that the transaction can proceed, and brings back a response. In return, businesses typically pay fees. These may include a percentage of each transaction, a fixed per-payment charge, or other costs, depending on the provider and agreement.
Why Does It Matter?
Payment processing affects more than the fee charged for a sale. A dependable, straightforward system can reduce failed transactions, save staff time, help customers pay in the way they prefer, and make it easier to keep accurate records. Faster, more convenient checkout may also help prevent customers from abandoning a purchase.
Small improvements can have a meaningful effect when repeated across hundreds or thousands of transactions. The goal is not simply to choose the cheapest advertised rate. It is to understand the total cost and find a reliable solution that suits how your business sells.
Understand Your Total Processing Costs
Before changing providers, learn what you currently pay. Review statements for transaction fees, monthly charges, equipment costs, chargeback fees, and any extra fees for specific payment methods. A chargeback happens when a customer disputes a payment and asks their bank to reverse it.
Compare costs across a typical month, not just one transaction. A low percentage may come with substantial monthly charges, while a simple flat rate may be easier to predict. Ask providers to explain any unclear line items in plain language.
Choose Pricing That Fits Your Sales
Processors may use different pricing models, such as a flat rate or interchange-plus pricing. Interchange is a fee set by the card payment system and the customer's bank; the provider adds its own charges. No one model is best for every business. Compare offers using your average transaction size, sales volume, and mix of in-person and online payments.
Request a written quote based on your real sales data. This is more useful than relying on a headline rate that may not apply to your transactions.
Match the Solution to How You Sell
A shop, an online store, and a business that takes payments at customers' homes have different needs. Look for a solution that supports your main sales channels, such as in-person terminals, online checkout, invoices, or mobile payments. Using compatible tools can reduce manual work and avoid paying for features you do not need.
Use Integrated Tools to Save Time
Integration means connecting payment software with other business tools, such as accounting or inventory systems. When systems share information, staff may spend less time entering the same sale twice and fixing errors. For example, a payment could automatically appear in your bookkeeping records and update stock levels.
Ask whether an integration is included or carries an extra fee, and check that it works with the tools you already use.
Encourage Efficient Payment Methods
Some payment methods may cost your business less than others, but availability and fees vary. Review your processor's pricing to see whether digital wallets, bank payments, or other options could be cost-effective for your customers and business. Make convenient options visible at checkout without pressuring customers or misrepresenting costs.
Reduce Avoidable Errors and Failed Payments
Incorrect payment details, duplicate charges, and unclear checkout instructions can create extra work and disputes. Use clear forms, confirm order totals, and train staff to check amounts before completing in-person payments. For recurring payments, keep customer contact and billing details up to date, with permission.
Protect Payments and Prevent Disputes
Security measures help protect customer information and reduce the risk of fraud. Use reputable providers, keep software updated, limit who can access payment tools, and follow the provider's security guidance. Keep receipts and order records so you can respond promptly if a customer questions a charge.
Also make your business name recognizable on statements and provide clear refund and delivery policies. These simple steps can prevent confusion that might otherwise lead to a dispute.
Review Your Provider and Negotiate
Payment needs change as a business grows. Review statements regularly and compare your current costs with offers from other providers. If you have steady sales, ask your provider whether it can offer better pricing or remove services you no longer use. Before switching, check contract terms, cancellation fees, equipment requirements, and how long it takes to receive funds.
Getting Started: First Steps for Beginners
- Collect three recent processing statements and calculate your average monthly cost.
- List how you accept payments and which tools need to connect to your processor.
- Request comparable written quotes from at least two providers.
- Compare total costs, reliability, support, security, and contract terms—not just the advertised rate.
- Test any new system with a small number of transactions before fully switching.
Common Mistakes to Avoid
- Choosing a provider based only on its lowest advertised rate.
- Ignoring monthly, equipment, cancellation, or dispute-related fees.
- Switching without checking whether your checkout, accounting, or inventory tools are compatible.
- Overlooking customer experience: a confusing or unreliable checkout can cost more in lost sales than it saves in fees.
- Failing to review statements after setup, when unexpected charges may first appear.
Resources and Next Steps
Start with your processor's pricing schedule, service agreement, and security documentation. Your accountant or bookkeeper can help interpret how processing costs affect your records. You can also consult trusted small-business organizations and payment-provider comparison resources, checking how each source handles sponsored recommendations.
You do not need to make every change at once. Begin by finding one fee you do not understand, then ask your provider to explain it. That simple first step can reveal where your business may be able to save.