
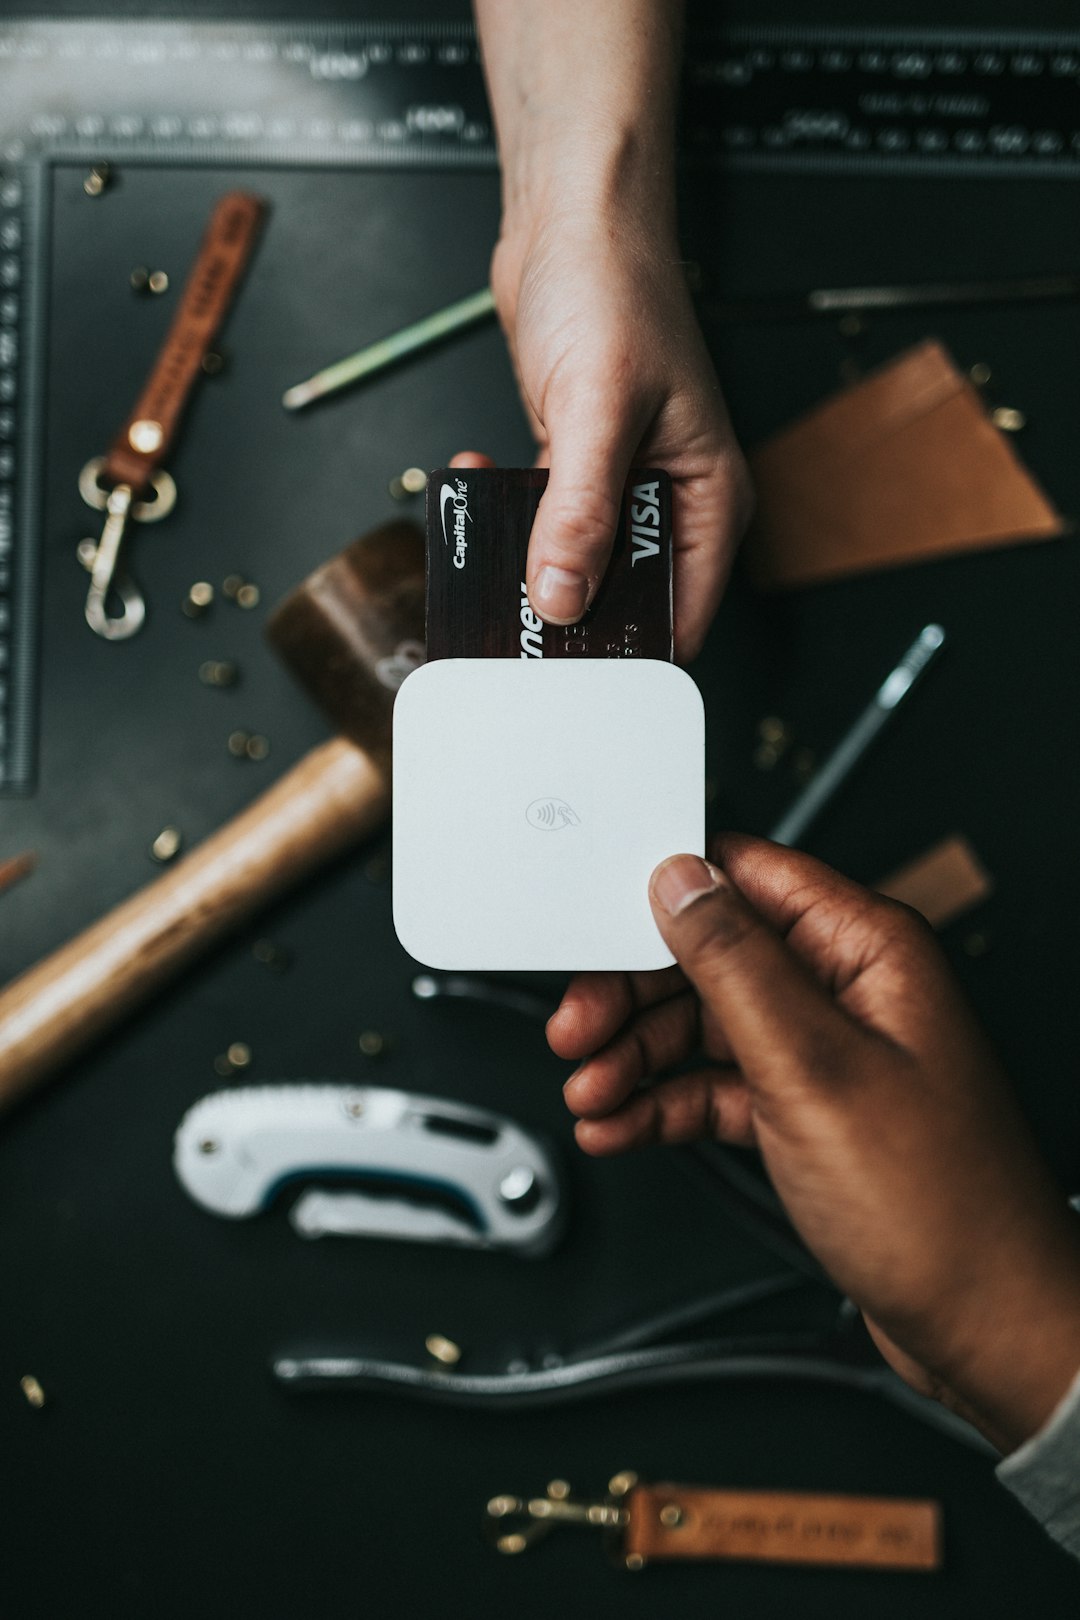

Choosing credit card processing services affects how easily customers pay, how quickly you receive funds, and what you spend on each transaction. This guide explains how payment processing works, what fees and features to compare, and how to evaluate credit card processing companies—so you can choose a setup that suits your business. If you are ready to get started, you can create a merchant account online and then apply.
Key Takeaways
- Compare total processing costs, not just the advertised transaction rate.
- Match payment options and integrations to how your customers buy.
- Review security, funding schedules, contract terms, and support before choosing a provider.
How does credit card processing work?
A card payment travels through several parties. The payment processor routes transaction information between your business, the acquiring bank, the card network, and the customer's issuing bank. The issuer approves or declines the charge, and the result returns to your point-of-sale system or online checkout.
Behind that quick response are authorization, authentication, clearing, and settlement steps. The full cost may include interchange fees, card-network assessments, and the processor's own markup. Understanding these components makes it easier to compare offers and spot pricing that looks simple but leaves important charges unclear.
Which payment processing services does your business need?
Start with the way you sell. A shop may need a countertop terminal and contactless payments, while an online seller may prioritize a hosted checkout, payment gateway, and tools for managing recurring billing. Businesses selling both in person and online often benefit from connected systems that bring transactions and reporting together.
Consider the payment methods your customers actually use, such as credit and debit cards, digital wallets, and contactless cards. Ask whether the service supports refunds, tips, recurring charges, invoicing, and integrations with your accounting or inventory software. The right feature set should simplify checkout without forcing you to pay for tools you will not use.
How can you compare credit card processing companies?
Compare providers on more than the headline rate. Request a clear breakdown of transaction fees, monthly charges, equipment costs, chargeback fees, and any cancellation or minimum-processing terms. Ask how and when funds are deposited, whether hardware is purchased or leased, and what customer support is available when a payment issue interrupts business.
Pricing models commonly include flat-rate, interchange-plus, and tiered structures. Flat-rate pricing can be easier to understand, while interchange-plus separates underlying card costs from the processor's markup. The best fit depends on your transaction mix and business needs; review a sample statement or written quote rather than assuming one model is always cheapest.
Security and compliance matter just as much as price. Ask how the provider supports secure card-data handling, tokenization, fraud controls, and PCI DSS responsibilities. The PCI Security Standards Council's PCI DSS overview explains the standard designed to protect payment account data; confirm what requirements apply to your particular setup with your provider.
What should you check before applying?
Prepare basic business information, including your legal business name, contact details, business type, estimated sales, and the channels where you accept payments. Depending on the provider and application, you may also be asked for ownership details, banking information, or supporting documents. Accurate, consistent information helps the review proceed smoothly.
Before accepting an offer, read the agreement carefully. Confirm the pricing model, funding schedule, equipment terms, renewal and cancellation provisions, and procedures for disputes or chargebacks. If a term is unclear, ask for an explanation in writing. A dependable provider should be able to describe both the service and its costs in plain language.
What do processing costs look like in practice?
Consider a small retailer that takes payments at a physical checkout and through an online store. It may need a card terminal, a payment gateway, and reporting that distinguishes in-person from online sales. Comparing the combined monthly costs and transaction charges across those channels gives a more useful picture than looking at a single advertised rate.
Costs vary with factors such as card type, how a payment is accepted, transaction volume, and provider pricing. For example, an online transaction and a tap-to-pay purchase may be priced differently under a given agreement. Use your own sales estimates and ask providers to show how their quoted fees would apply to your expected mix; avoid relying on a generic savings claim.
How can you take the next step?
Make a short list of must-have features, estimate your monthly payment volume, and compare written offers for total cost, security, support, and contract flexibility. When you are ready to begin, click here to apply. You can create a merchant account from that link; create your account first, then submit your application.