
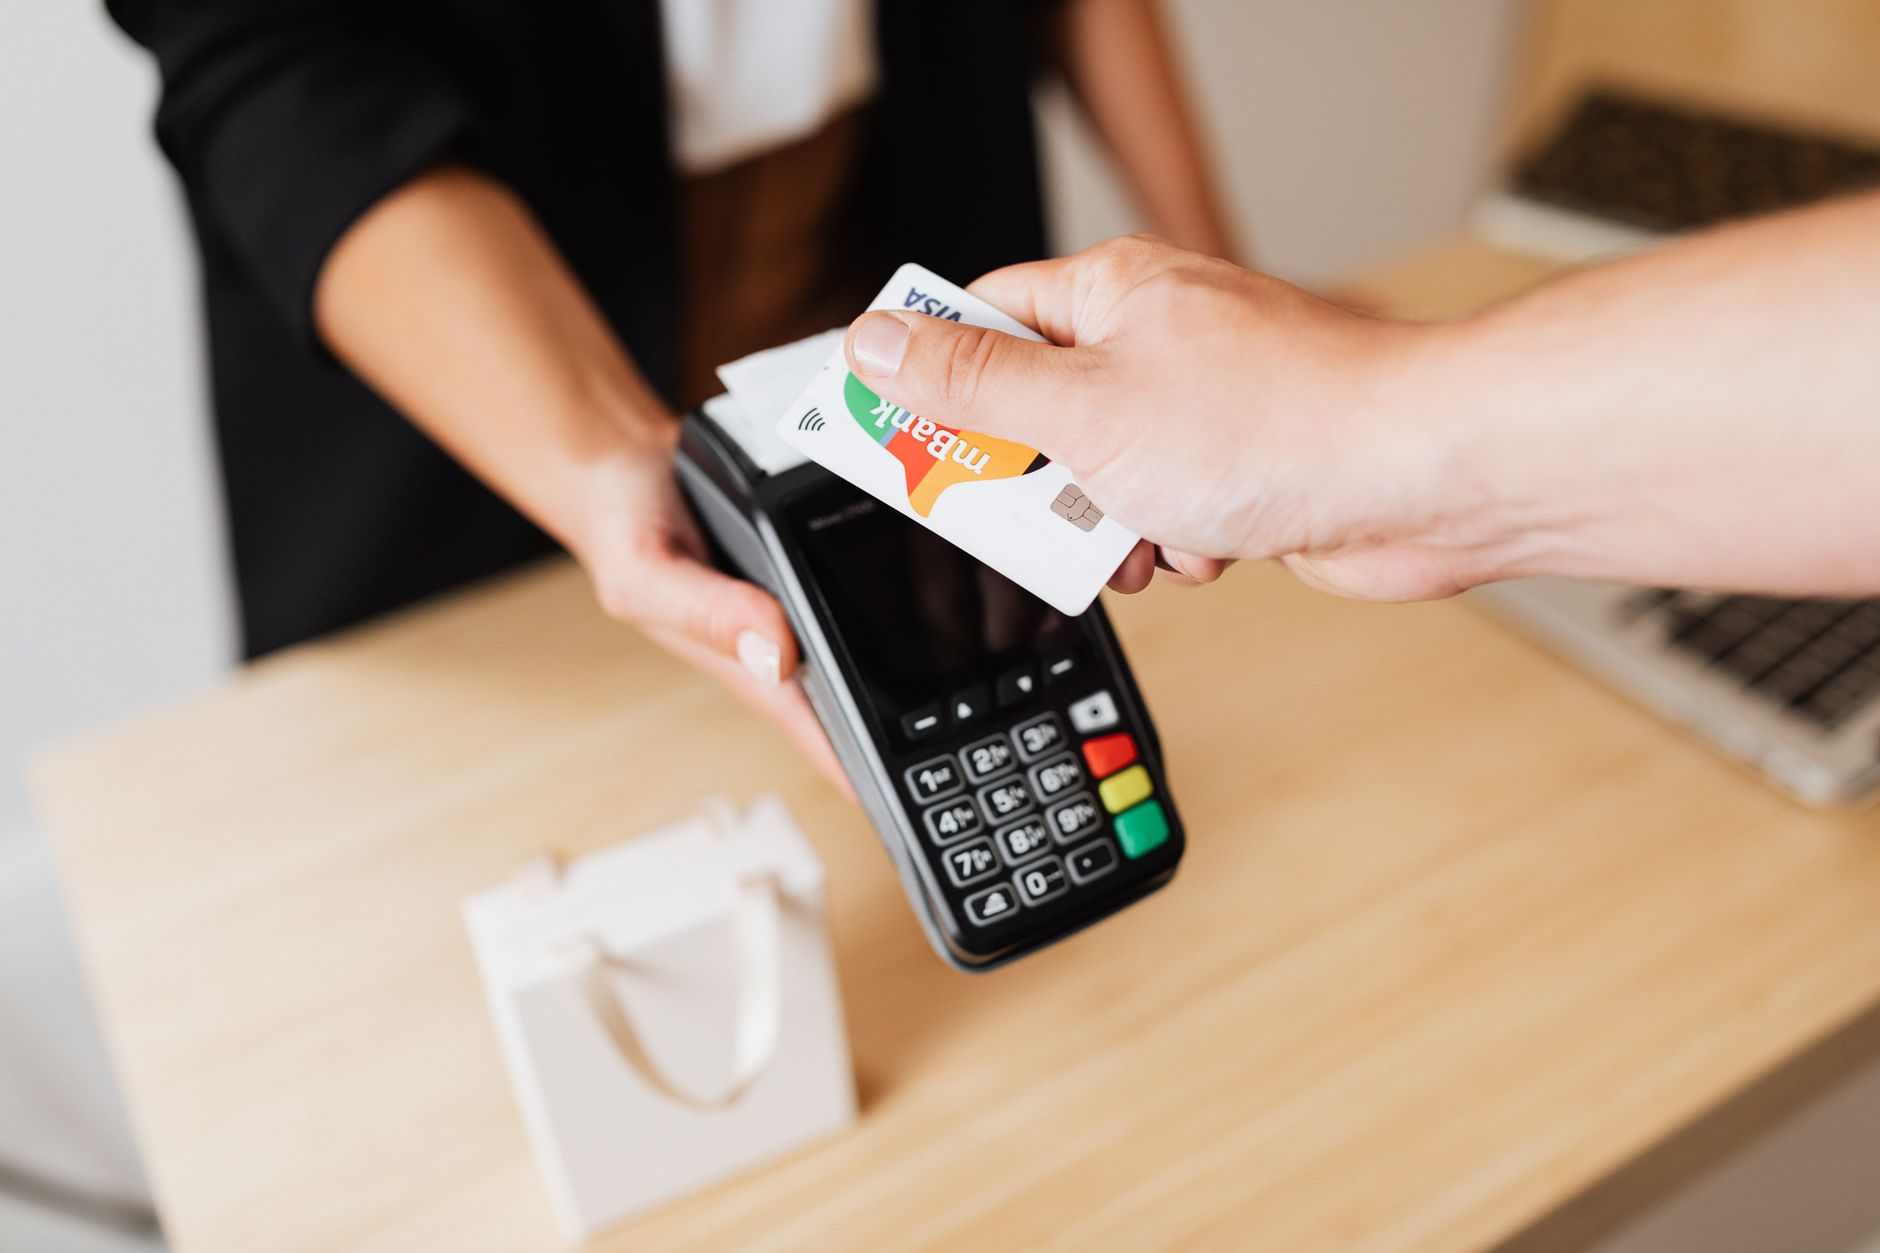

In this practical guide you will learn how to evaluate credit card processing options, compare credit card processing services, and quickly create a merchant account so you can start accepting payments. Within the first read you'll understand fee drivers, security requirements, and the exact next step to apply for a merchant account with a trusted processor.
- Understand which fee components affect your cost and how to negotiate them.
- Know the security and compliance basics that credit card processing companies enforce.
- Follow a single, fast step to create a merchant account and apply to start processing.
How can I choose a credit card processing service that lowers my costs?
Start by separating the core elements: interchange, processor markup, and gateway fees. Interchange is set by card networks and is non-negotiable for most merchants; the processor markup (transaction, monthly, and equipment fees) is negotiable. Look for transparent pricing models—flat-rate, interchange-plus, or tiered—and simulate your monthly volume to compare true costs across offers.
Evaluate bundled services: POS integration, reporting dashboards, and chargeback management. If you accept online payments, factor in gateway or tokenization fees. Ask potential credit card processing companies for sample statements and a breakdown of all fees tied to your merchant category code (MCC).
How do credit card processing companies protect transactions and reduce fraud?
Top providers layer technical controls—EMV chip acceptance, end-to-end encryption, tokenization, and fraud scoring—to cut liability and chargebacks. Tokenization replaces card details with a non-sensitive token so stored credentials are not reusable if breached.
Compliance is equally important: processors and merchants must adhere to industry controls. For a concise explanation of the standards that govern cardholder data protection, see the PCI DSS guidance from the official standards body: PCI DSS guidance. Choosing a processor that supports secure integrations (server-to-server tokenization or certified gateways) lowers your operational risk.
What operational outcomes should I expect from modern credit card processing companies?
Expect faster settlements, clearer reconciliation, and automated dispute workflows. Modern platforms provide same-day or next-day funding options, detailed transaction metadata for accounting, and real-time analytics to spot trends like refund spikes or fraudulent patterns.
Also prioritize service-level commitments: uptime guarantees for gateways, prompt onboarding support, and transparent underwriting terms. These factors determine how reliably you can accept payments during peak demand.
Examples and expert-backed context
Example 1: A retail merchant migrating from a tiered plan to an interchange-plus structure typically gains visibility into the per-transaction interchange component—this can reveal opportunities to reduce costs by steering transactions to lower-cost routing or adjusting acceptance methods (e.g., card-present vs. card-not-present).
Example 2: Restaurants and high-risk verticals should confirm whether the provider offers integrated tipping, automated gratuity capture, and specialized chargeback dispute workflows—these services materially affect net revenue and operational efficiency.
Expert context: Security frameworks and certifications remain central to risk management. Processors that publish compliance attestations and provide developer documentation for secure integrations reduce your engineering burden and liability exposure.
How quickly can I create a merchant account and start accepting cards?
Time to activation varies by underwriting requirements and documentation. For many standard retail and e-commerce businesses, the process is a few hours to a few days: create an account, provide business verification documents, and connect your bank for funding. Specialized or high-risk industries may require more extensive underwriting and longer timelines.
To get started immediately, you can create a merchant account through a streamlined application flow that captures business details, ownership verification, and banking information. Once approved, integrate a payment gateway or use built-in checkout tools to begin accepting cards.
Practical next step
If you want to begin the merchant account process right now, you can create an account and then complete the application through this processor— click here to apply... The link opens a streamlined onboarding where you simply create an account and submit your application.
Choosing the right credit card processing company comes down to transparent pricing, proven security controls, and operational reliability. Start by mapping your transaction mix, request sample statements, and initiate a short application to see precise pricing for your business. The fastest practical next step is to open the application above and compare the real quotes you'll receive once underwriting is complete.