
This guide explores upcoming innovations in payment technology and explains how businesses can adapt to stay ahead. You will learn what modern payment systems are, why they matter to your business, the core concepts shaping the future, practical first steps to get started, common pitfalls to avoid, and where to go next to deepen your knowledge. No prior technical experience is needed—this guide builds from simple ideas to more advanced ones using real-world examples and friendly analogies.
What is a payment system?
A payment system is any method or chain of tools that moves money from a buyer to a seller. At its simplest, it could be cash exchanged at a counter. Today, payment systems include credit and debit cards, mobile wallets, bank transfers, online checkout tools, and new digital currencies. Think of a payment system like a postal service for money: it takes value at one point and delivers it securely, quickly, and traceably to another point.
Why does it matter?
Payments are the life blood of every business. How customers pay affects the speed of transactions, customer satisfaction, cash flow, fraud risk, and even your brand image. Adapting to new payment technologies can:
- Increase sales by offering convenient ways to pay.
- Reduce costs and errors with automation and faster settlement.
- Reduce fraud with better security tools.
- Open new markets by enabling cross-border and digital-first customers.
Businesses that prepare now will be better positioned to capture opportunities as consumer habits and regulations evolve.
Core concept: Digital wallets and mobile payments
Definition: A digital wallet stores payment information on a smartphone or other device, allowing consumers to pay without physical cards. Examples include Apple Pay, Google Wallet, and Samsung Pay.
How it works (simple)
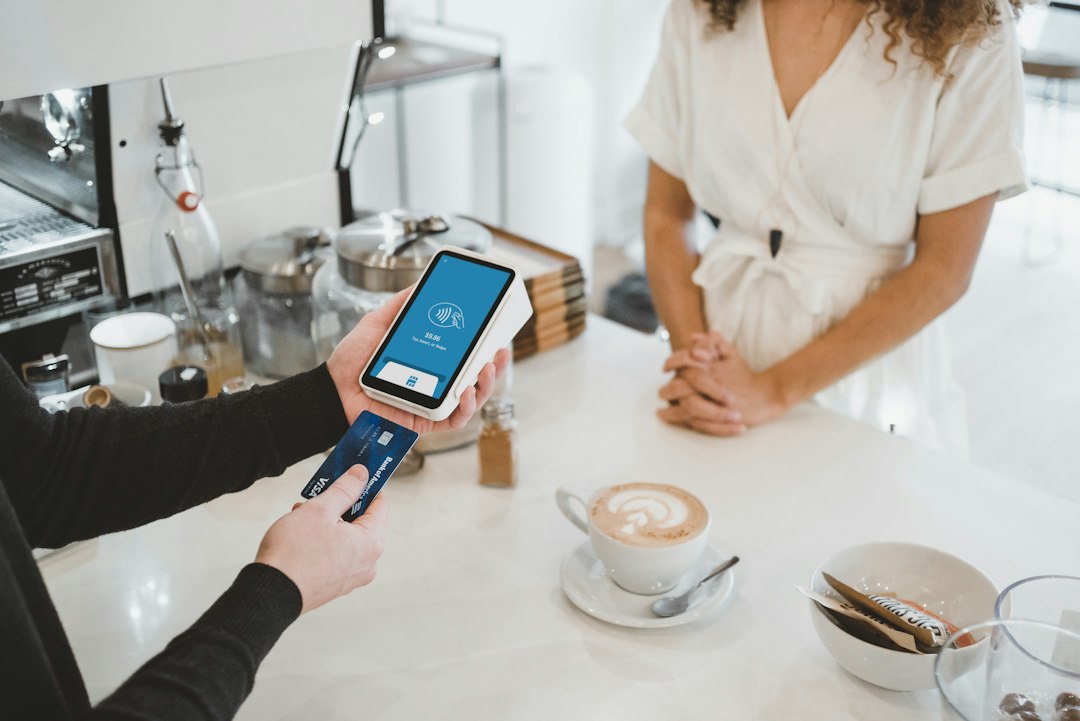
When a customer taps their phone at a contactless terminal, the wallet sends a secure token (a substitute for the real card number) to the terminal to authorize the payment. This is similar to using a ticket with a barcode instead of asking for your ID—fast and secure.
Business impact
Accepting mobile payments can speed up checkout, reduce queues, and appeal to younger, tech-savvy shoppers. For online businesses, digital wallets often simplify one-click purchases.
Core concept: Contactless payments and NFC
Definition: Contactless payments use Near Field Communication (NFC) or similar short-range wireless technologies so customers can tap a card or phone to pay. "NFC" is the technology enabling devices to communicate within a few centimeters.
Real-world analogy
Imagine unlocking a car with a key fob—no insertion required, just a near touch. Contactless payments are the same idea applied to money.
Core concept: Instant payments and real-time rails
Definition: Instant payments are bank transfers that settle within seconds, rather than hours or days. "Rails" are the underlying networks that move payments—like the highway system for money.
Why it matters
Real-time payments improve cash flow and reduce settlement risk for businesses. Think of it as getting paid immediately after a sale instead of waiting for the money to clear.
Core concept: Tokenization and security
Definition: Tokenization replaces sensitive payment data (like card numbers) with a unique token. The token is useless if intercepted. This reduces the chance that hackers can steal real data.
Analogy
Tokenization is like using a locker number rather than carrying a valuable item in your pocket—if someone learns the locker number, it is meaningless without the key managed by the locker system.
Core concept: Cryptocurrencies and blockchain
Definition: Cryptocurrencies are digital currencies secured by cryptography. A blockchain is a type of shared ledger that records transactions publicly or within a permissioned group. Not all blockchain uses involve cryptocurrencies, but both are often discussed together.
What businesses need to know
Cryptocurrencies enable new forms of payment—especially cross-border and programmable money—without traditional banks. However, they can be volatile and may require additional legal and tax handling. Some businesses accept stablecoins (cryptocurrencies pegged to stable assets) to reduce volatility.
Core concept: APIs and open banking
Definition: An API (Application Programming Interface) is a way for software systems to communicate. Open banking refers to regulated systems where banks share customer-allowed data with third parties via APIs.
Why APIs are powerful
APIs let your point-of-sale, inventory, and accounting systems talk to payment processors automatically. That means fewer manual steps and fewer mistakes—like having a translator connect different departments in a business so they all understand each other instantly.
Core concept: Biometric authentication
Definition: Biometrics use physical traits—like fingerprints, facial recognition, or iris scans—to verify identity. Biometric authentication can replace or complement passwords and PINs.
Considerations
Biometrics can speed up checkout and reduce fraud, but businesses must respect privacy rules and store biometric data securely using specialized services rather than holding raw biometric data themselves.
Core concept: AI and fraud detection
Definition: Artificial Intelligence (AI) can analyze transaction patterns to detect suspicious activity in real time. AI models can learn what normal behavior looks like and flag anomalies for review.
Practical benefit
AI helps reduce chargebacks (when customers dispute transactions) and prevents fraudulent orders before they ship—similar to a guard dog that learns family members' patterns and alerts you to intruders.
Getting started: First steps for beginners
1. Assess customer preferences: Ask your customers how they like to pay—card, mobile wallet, bank transfer, or otherwise. Small surveys or observing checkout habits give practical insight.
2. Audit your current setup: List the payment methods you accept, your processor fees, settlement times, and refund procedures. This gives you a baseline to improve from.
3. Start small and test: Add one new payment option (for example, a digital wallet or contactless terminal) in one location or channel before rolling it out everywhere.
4. Choose reputable partners: Work with established payment processors and POS (point-of-sale) providers that support tokenization and compliant security standards, like PCI DSS (Payment Card Industry Data Security Standard). If you see an acronym like PCI DSS, it just means a standard for keeping card data safe.
5. Automate reconciliation: Connect payments to your accounting system through APIs to reduce manual bookkeeping and speed up cash flow clarity.
6. Train staff: Teach employees how to handle new terminal types, refunds, and suspicious transactions. A confident staff improves customer experience and reduces mistakes.
Common mistakes to avoid
- Assuming one size fits all: Different customer segments prefer different payment methods. Don't remove old options when adding new ones; offer choice.
- Neglecting security: Skimping on tokenization, encryption, or secure partners to save costs can lead to expensive breaches.
- Ignoring fees and margins: New payment methods can come with fees. Compare costs and consider overall benefits like faster settlement or higher sales.
- Underestimating integration needs: Adding a payment method without connecting it to inventory and accounting can create manual work and errors.
- Failing to comply with regulations: Payments are regulated. Ensure you follow tax laws, anti-money laundering (AML) rules, and data protection laws like GDPR where applicable.
Resources and next steps for further learning
1. Industry blogs and reports: Follow payment-focused publications and reports from organizations like the Federal Reserve, World Bank, and major payment processors. They publish trend reports and best practices useful for business planning.
2. Vendor documentation and webinars: Many payment providers offer free guides, tutorials, and webinars explaining integration options and security practices.
3. Online courses: Look for beginner courses in digital payments, fintech fundamentals, or open banking on platforms such as Coursera, LinkedIn Learning, or Udemy.
4. Networking and forums: Join local business groups, chambers of commerce, or online communities where other merchants share real-world experiences and lessons learned.
5. Consult a trusted advisor: If you plan to accept cryptocurrencies, integrate advanced APIs, or expand internationally, consult with a payments expert or accountant who understands cross-border rules and tax implications.
Exploring the future of payment systems means paying attention to innovations—like contactless wallets, instant payments, tokenization, open APIs, biometrics, and AI-driven fraud detection—and understanding how each one could change the customer experience and operational flow. Businesses that adapt are not only protecting themselves from risk but also unlocking new revenue opportunities and efficiencies.
You're ready to take the first step: pick one small change to test this month—maybe accept a popular mobile wallet, enable contactless terminals, or connect your payment processor to your accounting system. That small experiment will teach you faster than any long plan, and you'll build confidence to scale further.
Be confident: learning and adapting to payment innovations is a gradual process, and small, steady improvements will keep your business ready for the future.