
This article explains what to evaluate and the practical steps to select credit card processing services that match your business needs. Within minutes you'll learn how credit card processing works, which cost and security factors to prioritize, and how to compare credit card processing companies for reliability and regulatory compliance.
- Key Takeaways: prioritize PCI compliance, total cost (interchange + markup), and transaction flow (gateway vs. processor).
- Look for tokenization, EMV/NFC support, clear fee breakdowns, and responsive dispute management.
What components make up credit card processing and why do they matter?
Credit card processing is a multi-step flow involving the cardholder, merchant, payment gateway, payment processor, and acquiring bank. Each component affects speed, security, and cost.
Understanding these roles lets you identify where fees originate (interchange and assessment) and where service differences appear (gateway features, settlement timing, and chargeback handling).
How do I evaluate pricing models among credit card processing companies?
Ask providers for an itemized fee schedule: interchange passthrough, processor markup, monthly gateway fees, chargeback fees, and equipment costs. Avoid offers that only provide a blended rate without documentation.
Compare whether the company uses interchange-plus, flat-rate, or tiered pricing. Interchange-plus typically provides the most transparency for businesses with moderate to high transaction volumes.
What security and compliance elements should influence my choice?
Prioritize providers that implement tokenization, end-to-end encryption (E2EE), and support EMV for card-present transactions and secure SCA (strong customer authentication) for card-not-present sales. Confirm that the provider's processes align with PCI DSS requirements.
For verification, consult the PCI Security Standards Council documentation to confirm the provider's compliance pathways and guidelines.
PCI Security Standards Council documentation
Which operational service levels should I require from a processor?
Define required uptime, settlement frequency, and customer support SLAs. Look for processors offering same-day or next-day settlement if cashflow is critical and clear escalation channels for chargeback disputes.
Assess fraud monitoring capabilities and real-time reporting tools; dashboards that provide reconciliation exports reduce accounting friction and speed problem resolution.
How can integrations and developer capabilities reduce long-term costs?
Inspect the payment gateway's APIs, SDKs, and plug-ins for your POS, e-commerce platform, or mobile app. Strong developer documentation, sandbox environments, and webhook support accelerate integration and reduce engineering time.
Providers that support hosted payment pages and tokenization can lower PCI scope and simplify audits.
What questions should I ask to compare providers directly?
- Can you provide sample merchant statements showing interchange and markup?
- How do you handle chargebacks and what are your average dispute win rates? (Ask for process, not necessarily statistics.)
- Which card networks and alternative payment methods (digital wallets, ACH) do you support?
- What are settlement timelines and hold policies for high-risk categories?
Examples, data points, and expert-backed context
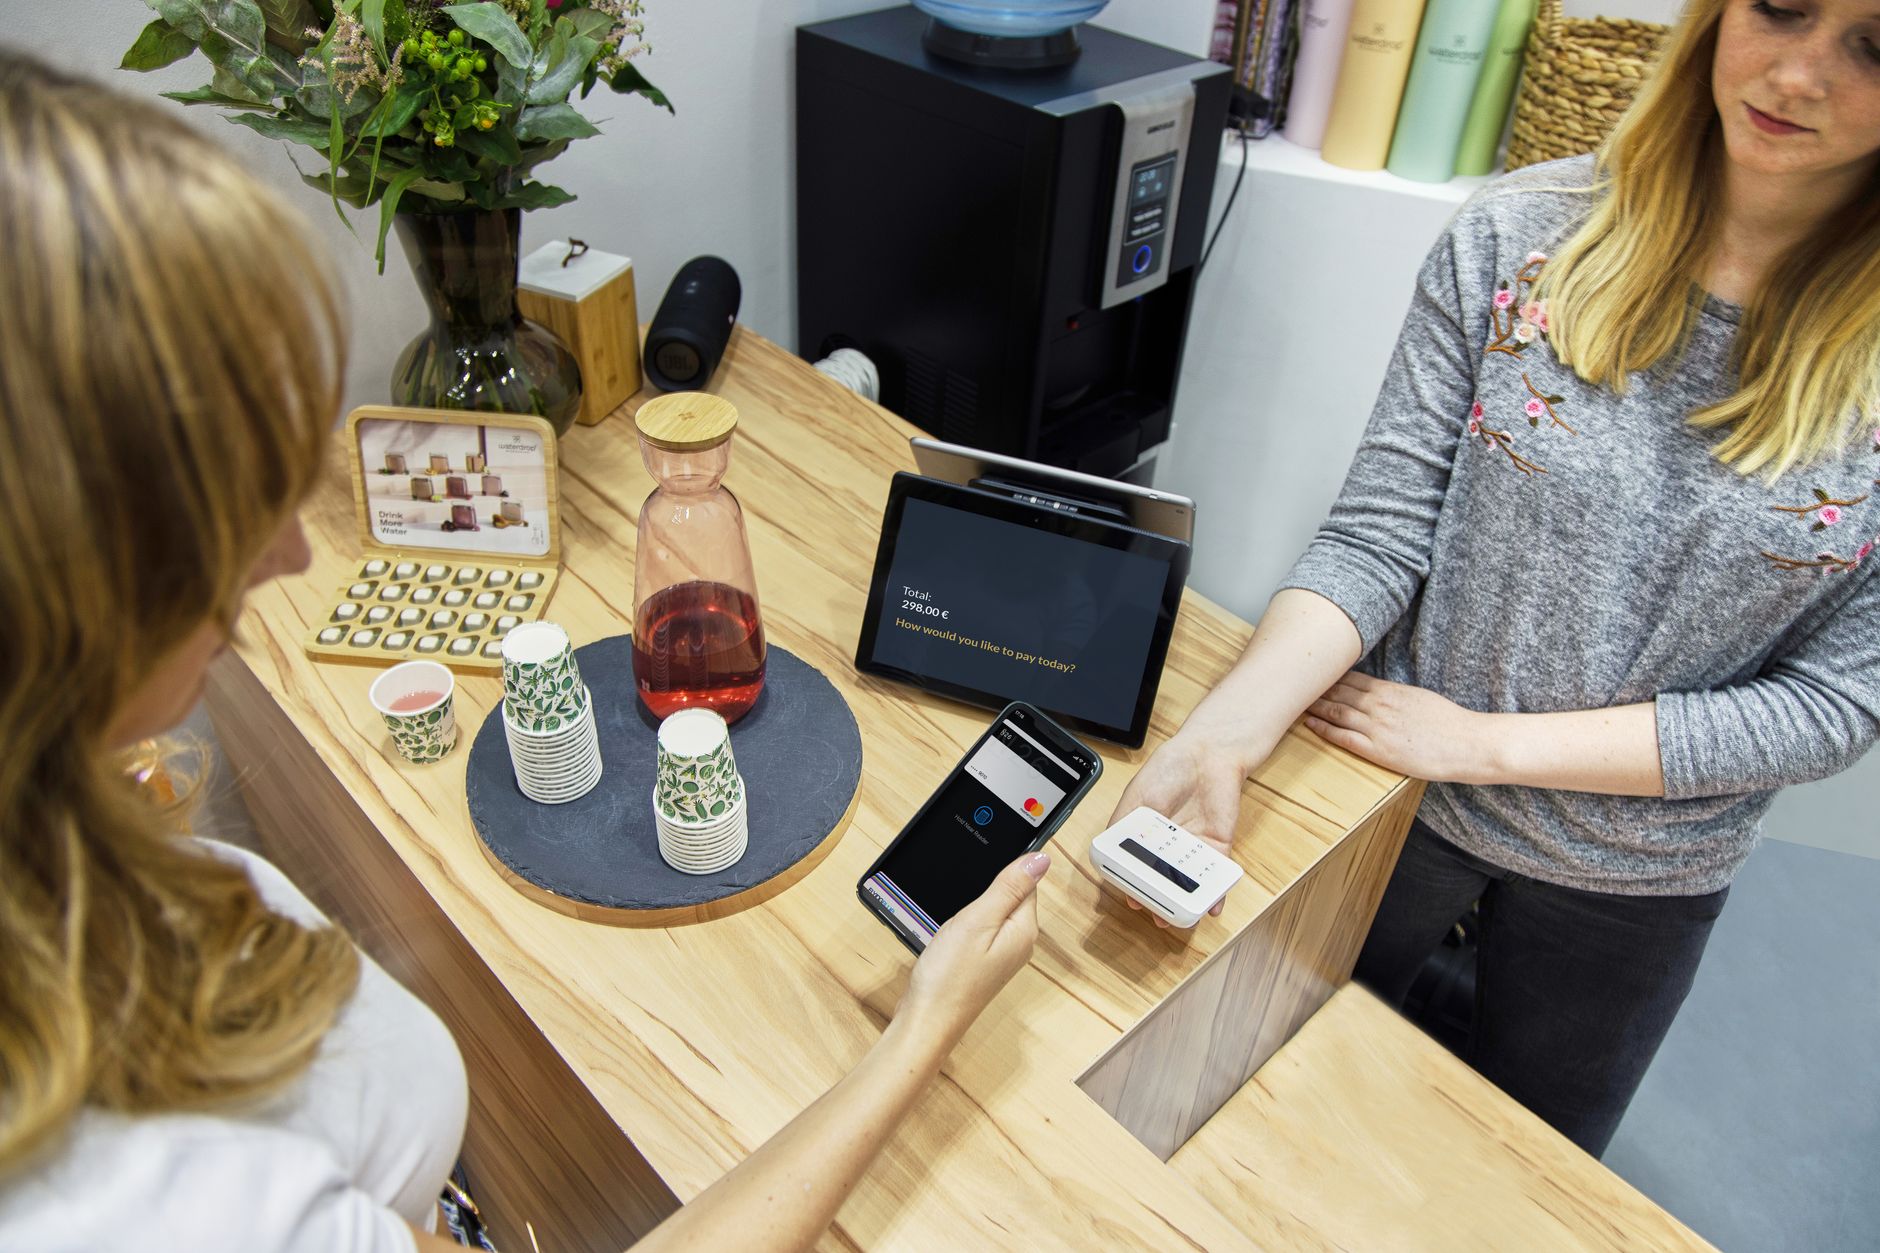
Example: A retail merchant prioritizing in-person payments should require EMV and NFC support to reduce counterfeit fraud and potential liability shifts. A subscription business should prioritize recurring-billing tokenization and dispute prevention tools to minimize card-not-present losses.
Expert context: industry guidance consistently emphasizes PCI scope reduction through tokenization and vendor-managed security as best practice; proving compliance documentation during procurement reduces onboarding delays.
How do change management and migration work when switching credit card processing companies?
Map current data flows, reconcile open batches, and confirm the new provider's onboarding checklist: MID setup, gateway integration, certificates, and webhooks. Schedule a cutover window with fallback procedures for a quick rollback if authorization failures occur.
Test transaction types—card-present, card-not-present, refunds, and partial refunds—before going live to avoid settlement and reconciliation surprises.
Vendor evaluation checklist (quick use)
Request demos; verify documented fees; confirm PCI-compliant tokenization; test API sandbox; validate SLAs for settlement and support; review contract terms for early termination fees.
Next step: compile three short-listed processors, request sample merchant statements and an onboarding timeline, and run a technical sandbox test to validate integration and security before signing a long-term contract.